Bretton Woods

1A Hotel in New Hampshire
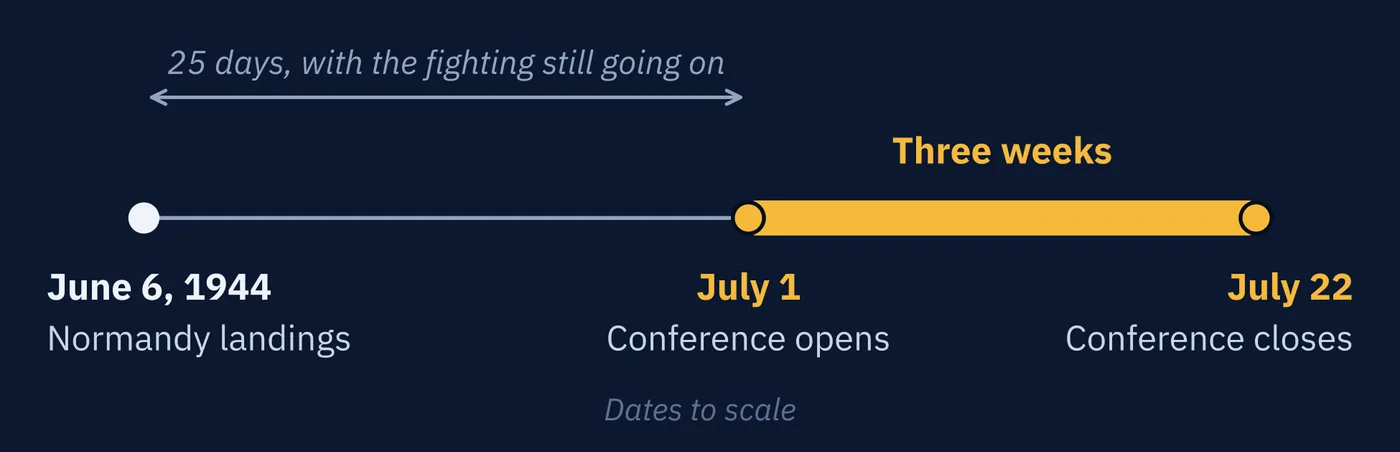
By the summer of 1944 the war in Europe had one likely ending. The Normandy landings had happened on June 6. The Soviet advance from the east could not be reversed. Germany would fall. The question was when.
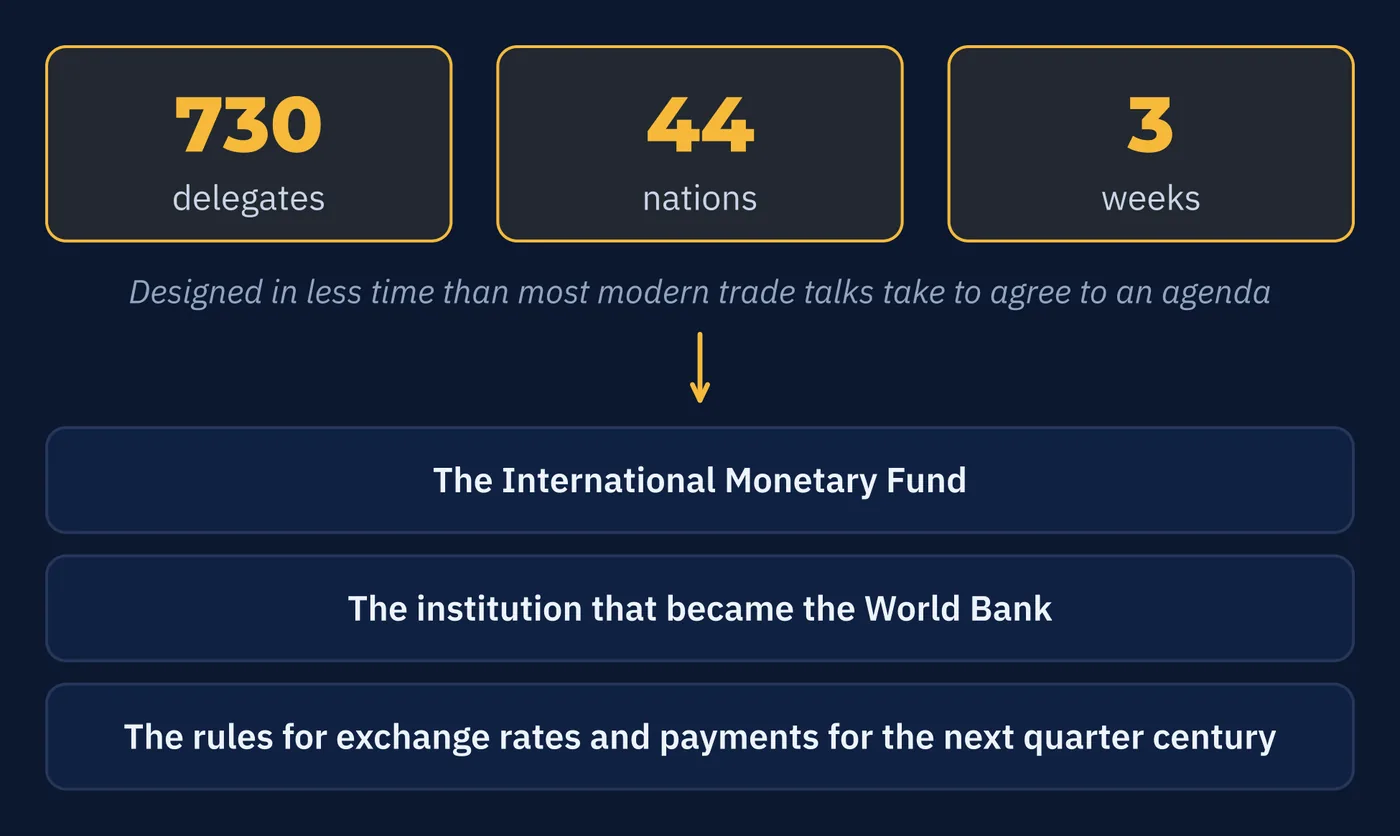
Twenty-five days after Normandy, with the fighting still going on, 730 delegates from 44 nations arrived at a resort hotel in New Hampshire.
They had come to answer a question nobody wanted left to chance. What would the world's monetary system look like when the shooting stopped?
The conference ran from July 1 to July 22. Three weeks.
In that time they created the International Monetary Fund. They created the institution that became the World Bank. And they wrote the rules for exchange rates and international payments for the next quarter century. It is one of the most concentrated pieces of design in history, done in less time than most modern trade talks take to agree to an agenda.
2The Brief Was Never Again
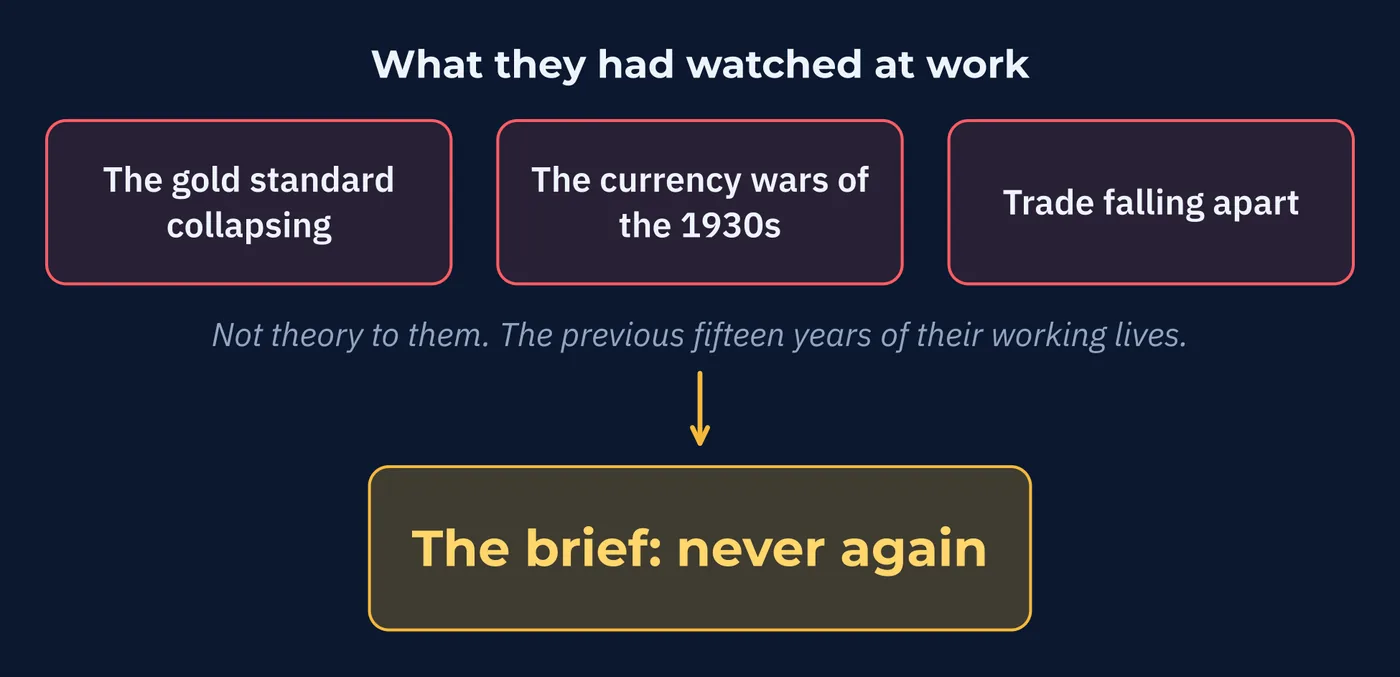
What made it possible was that the people in the room were not theorists.
They were policymakers who had watched the gold standard collapse, seen the currency wars of the 1930s, and lived through trade falling apart. Lesson 31 was not history to them. It was the previous fifteen years of their working lives.
Which gave the brief a specific shape. Not design an elegant system, but design a system that prevents this from happening again.
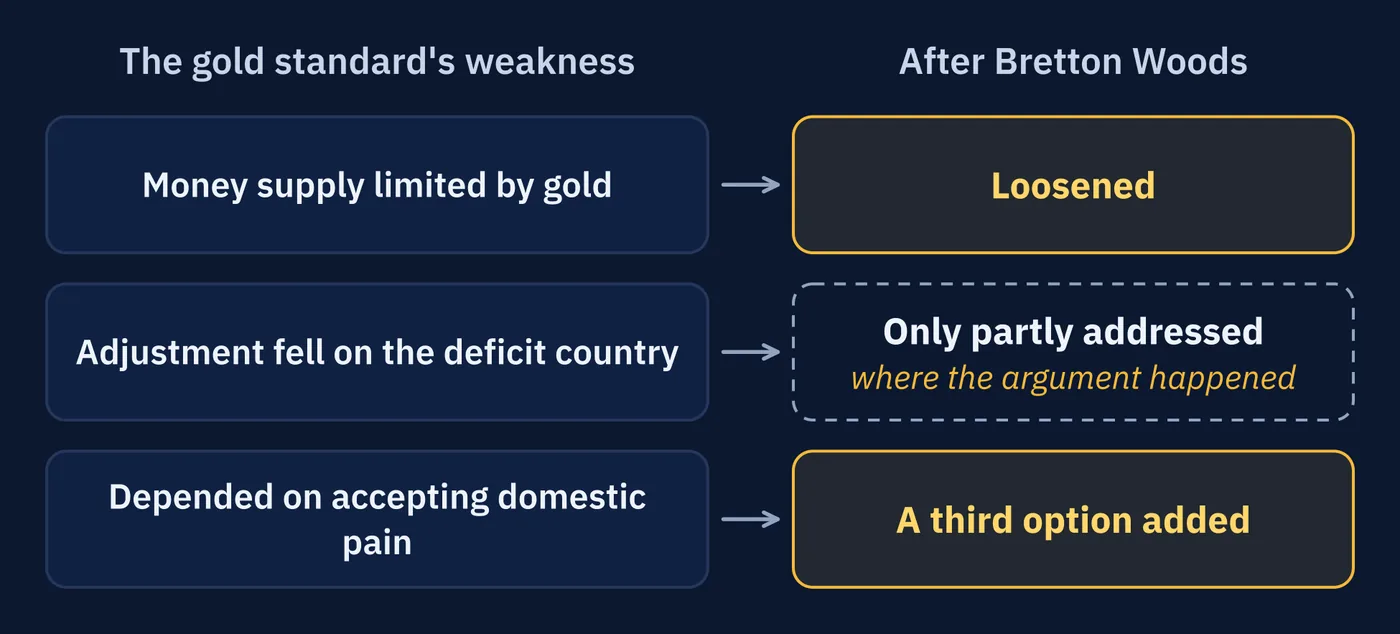
So what were they trying to fix? Lesson 31 named three weaknesses in the gold standard. The delegates knew all three.
| The Old Weakness | What Bretton Woods Did About It |
|---|---|
| Money supply limited by gold discovery | Loosened. The dollar could expand, and gold sat one step further back. |
| Adjustment fell on the deficit country | Keynes tried to fix this directly. He lost. It was only partly addressed. |
| Depended on governments accepting domestic pain | Gave them a third option, which is the subject of Section 6. |
Two out of three, and the middle row is where the argument happened.
3Two Plans
The conference had many participants and two architects.
John Maynard Keynes led the British delegation. You met him in Lesson 31, publishing the pamphlet that told Churchill exactly what would happen and being ignored. Harry Dexter White led the American one.
| Keynes | White | |
|---|---|---|
| The core idea | A supranational institution issuing a new international currency | A stabilization fund holding gold and national currencies |
| The reserve currency | A new unit called the bancor | The US dollar |
| At the center | An international body | The United States |
| Adjustment | Symmetric. Surplus countries pressured to adjust too. | Asymmetric, as before |
Look at the last row, because that was the important difference.
Keynes's design put pressure on both sides of an imbalance. A country running large surpluses would face a cost for hoarding. The burden of correction would no longer fall entirely on the country already in trouble.
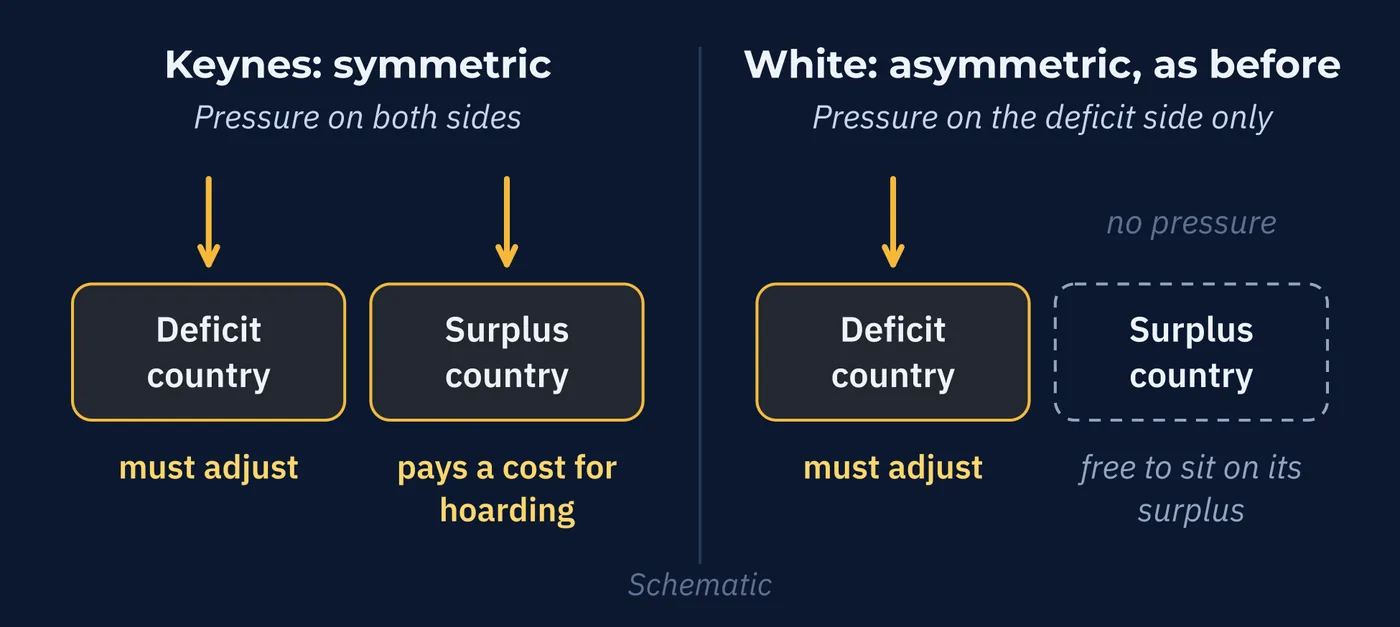
That is a direct fix for the flaw that made the gold standard so damaging. It was the best part of his proposal, aimed at the thing that had done the most harm.
It was not adopted.
4Why Keynes Lost
Not because his plan was worse. By most assessments then and since, Keynes was the better economist and the bancor was the better design.
He lost because of what each man stood behind.
| Keynes represented | White represented |
|---|---|
| A country exhausted by six years of war | A country whose industry had expanded during it |
| Deeply indebted, dependent on American support | Holding about two thirds of the world's monetary gold |
| A fading imperial power | About half of the world's manufactured output |
The intellectual argument belonged to Keynes. The power belonged to White.
The outcome was not a compromise between the two plans. It was White's plan, adjusted at the edges.
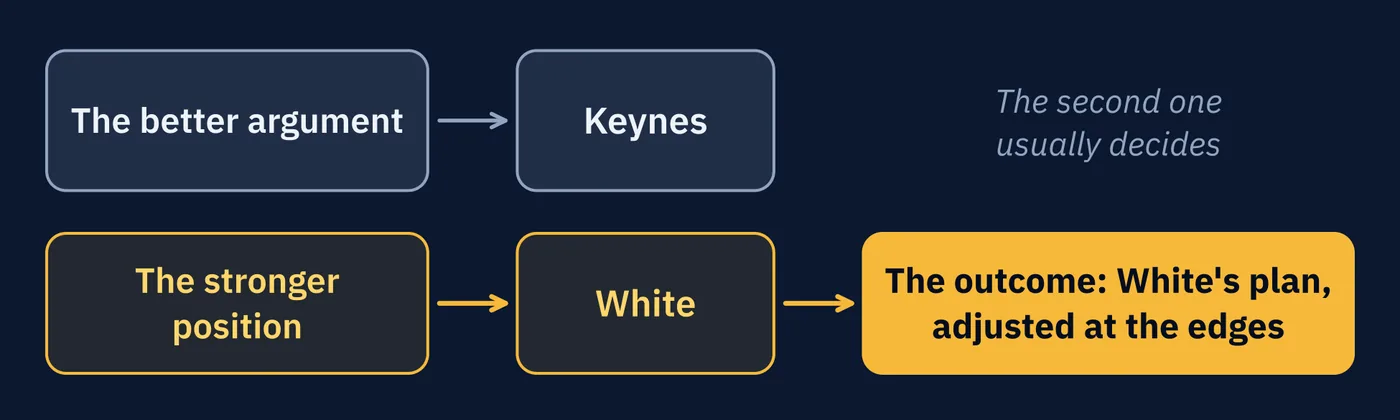
There is a wider lesson there. In international negotiations, the better argument and the stronger position are different things. The second one usually decides.
5How It Was Built
The architecture rested on a single promise.
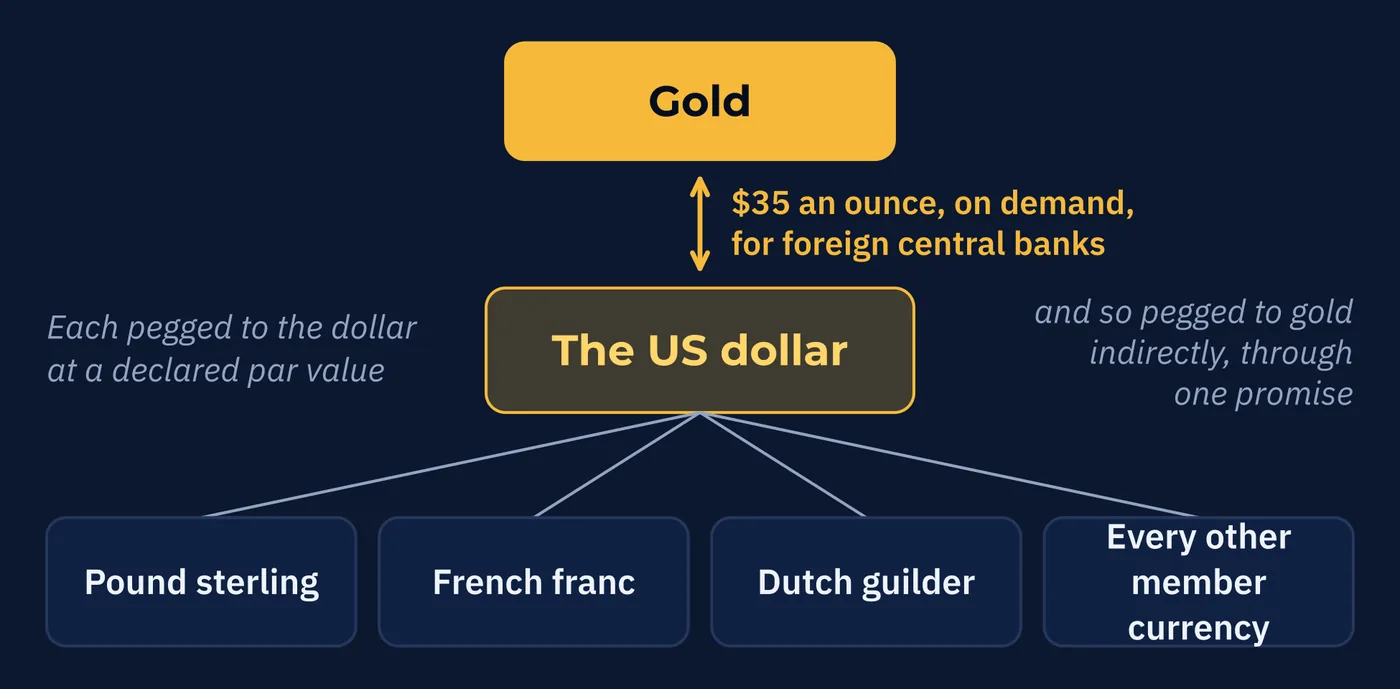
$35 per ounce of goldThe United States committed to convert dollars held by foreign central banks into gold at that rate, on demand. Not a statement of intent. A legal obligation.
Everything else hung off it. Every other currency was pegged to the dollar. So every other currency was pegged to gold indirectly, through that one promise.
| Element | How It Worked |
|---|---|
| The dollar | Convertible to gold at $35 an ounce for foreign central banks |
| Every other currency | Pegged to the dollar at a declared par value |
| The permitted band | Plus or minus one percent, held by central bank intervention |
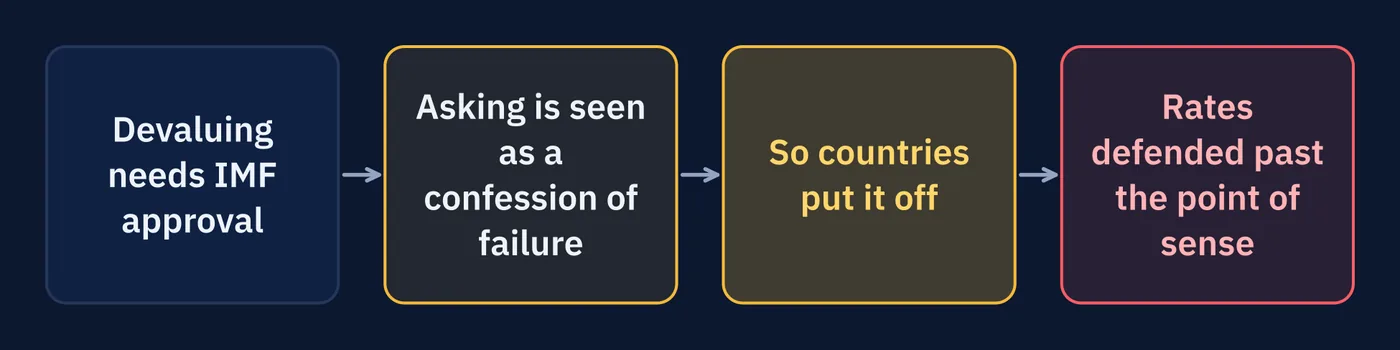
| Changing a par value | Required IMF approval, and was treated as an admission of difficulty |
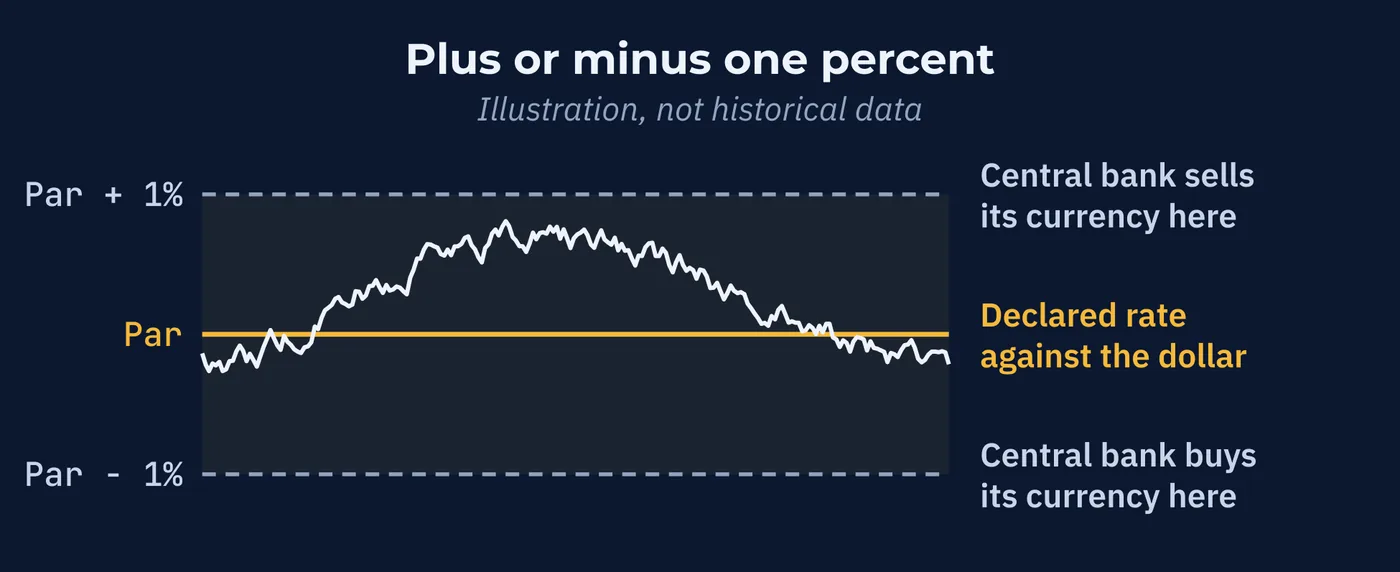
That last row matters more than it looks. A devaluation had to be requested, and it was seen as a confession of failure. So countries put it off. They defended rates long past the point where the defense made sense.
Which is the third step of Lesson 31's failure sequence, written into the rules.
6The Missing Third Option
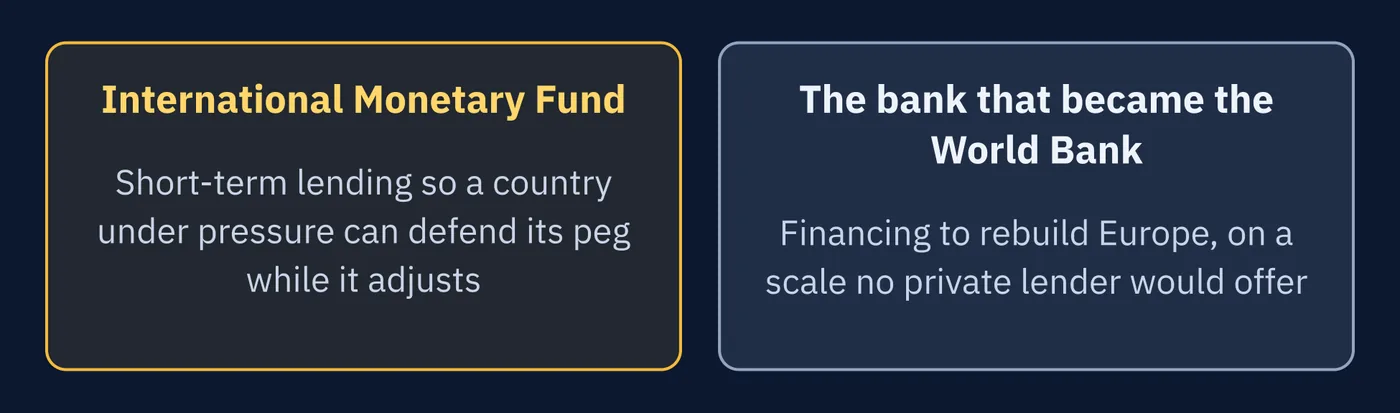
The IMF was created to solve one specific thing, and it is the piece that makes the rest of the system make sense.
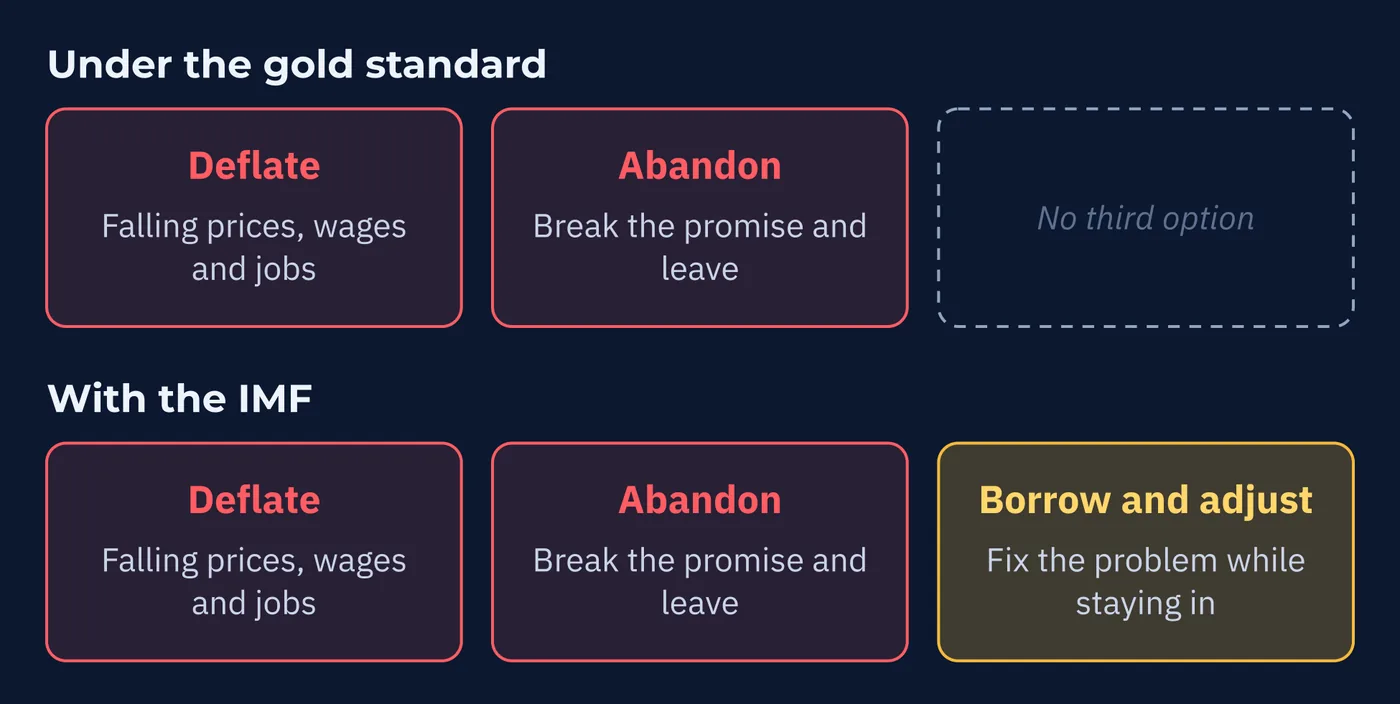
Under the gold standard, a country running out of gold had exactly two options.
| Option | What It Meant |
|---|---|
| Deflate | Accept falling prices, falling wages, and unemployment to defend the rate |
| Abandon | Break the promise, leave the system, and take the credibility damage |
Both are terrible, which is why the 1930s went as they did. When those are the only choices, countries eventually take the second, and their neighbors follow.
The IMF added a third.
Borrow, adjust gradually, and stay in the system. A country under pressure could borrow short-term to defend its peg while fixing the underlying problem, instead of choosing between severe pain and walking away.
The World Bank was created alongside it for a different problem. Rebuilding Europe needed financing on a scale no private lender would offer to countries whose infrastructure had been destroyed. Its mandate broadened a great deal in the decades after.
7Why the Dollar
Placing the dollar at the center can look, from here, like American ambition. It was mostly arithmetic.
In 1944 the United States held about two thirds of the world's monetary gold, roughly twenty billion dollars' worth. Every other major economy had spent its reserves on the war, lost them to occupation, or both.
It was also making about half of the world's manufactured goods. Its industry had not merely survived the war, it had expanded during it. In Europe and Japan, industry had been destroyed.
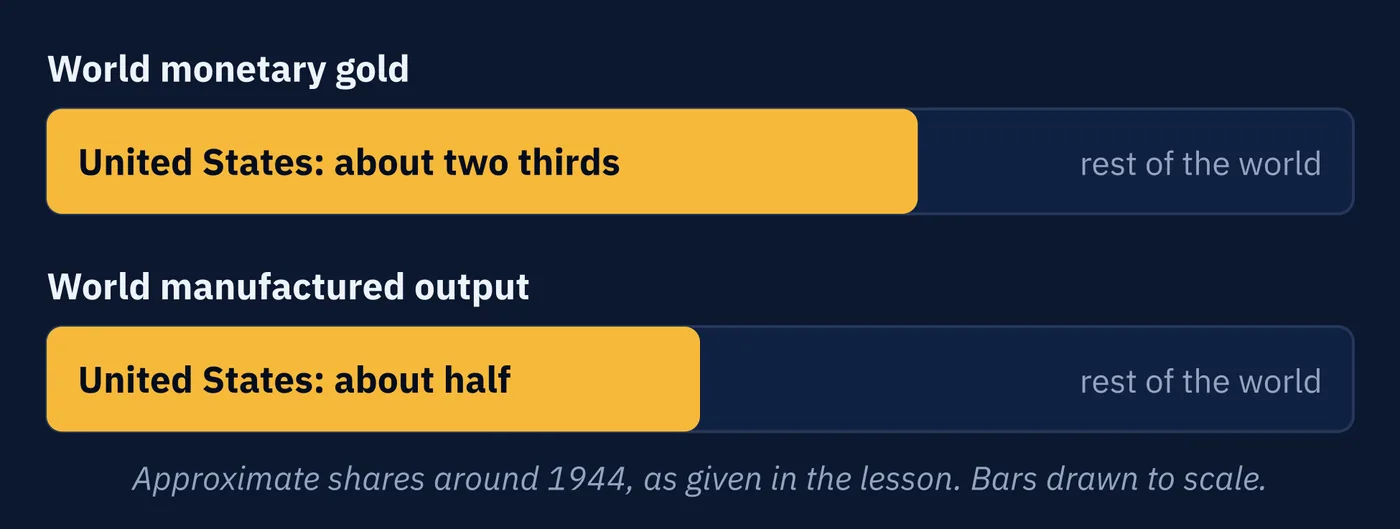
manufactured goods.
So the question at the conference was not really which currency should anchor the system. It was which currency could.
There was one candidate. That matters, because it makes the dollar's position a historical outcome rather than a permanent fact. What specific circumstances built, other circumstances can in principle unbuild.
Series G takes that question up directly.
8The Flaw in the Foundation
The delegates fixed most of what had gone wrong. And in doing so they built in something new.
The system needed the world to hold dollars. That was the point. Dollars were the reserve asset, the settlement currency, and the anchor for everything else. For trade to grow, the supply of dollars held abroad had to grow with it.
But the system also required every one of those dollars to be convertible into gold at thirty-five dollars an ounce.
Read those two sentences together and the problem appears.
The world needed more dollars than there was gold to back them.
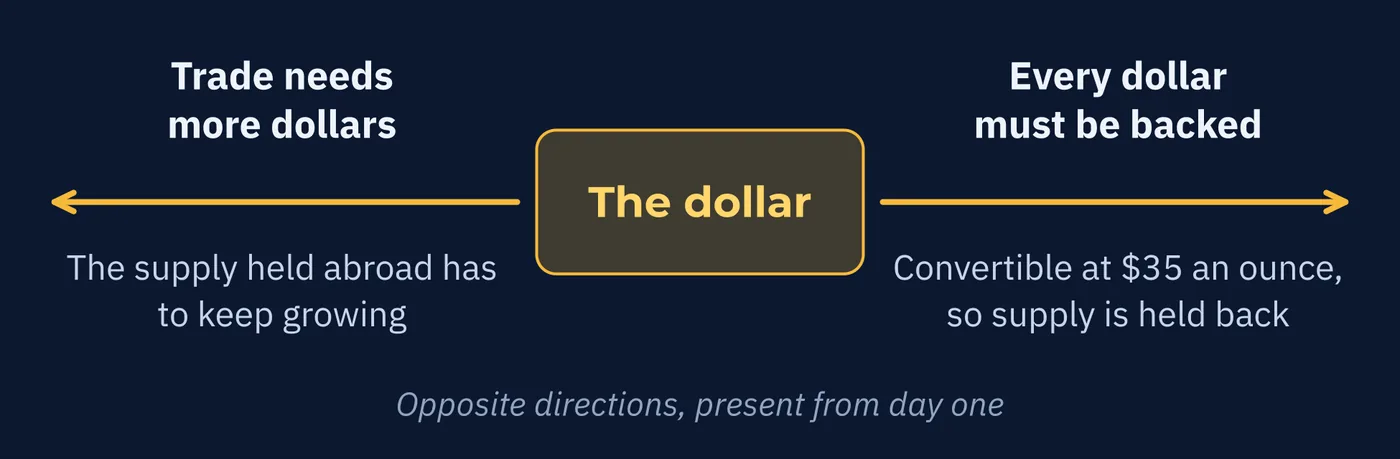
Supplying the world meant sending out more dollars than the gold could cover. Keeping every dollar backed meant restricting supply and starving trade of the reserves it needed.
The two requirements pointed in opposite directions, and no amount of careful management could reconcile them. This was not a policy error waiting to happen. It was a contradiction present in the design from day one.
The system lasted roughly a quarter of a century. It only ran fully as designed from 1958, when Europe's currencies became freely convertible, but post-war reconstruction, the growth of world trade, and decades of exchange rate stability all happened inside it.
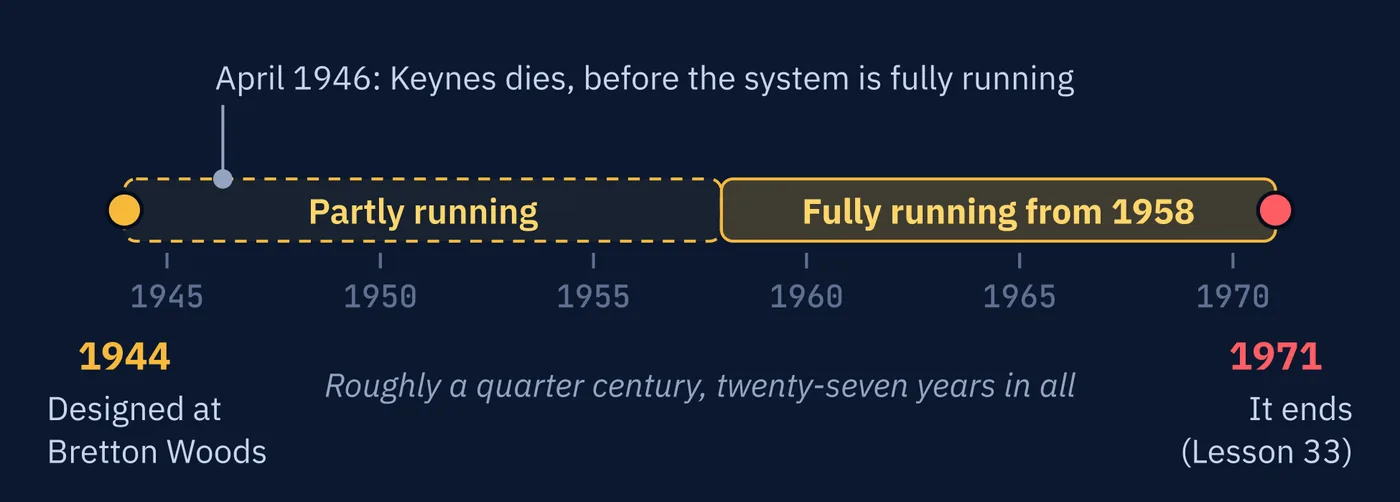
Then the contradiction came due. The next lesson is about the twenty-seven years it took, and the single afternoon in which it ended.
Three Things to Remember
Try This
Fifteen minutes. Mostly thinking rather than looking things up.
Words From This Lesson
| Term | What It Means |
|---|---|
| Bretton Woods | The 1944 conference, and the monetary system it created, which ran until the early 1970s. |
| Bancor | Keynes's proposed international reserve currency, issued by a supranational body. Never adopted. |
| Symmetric adjustment | A mechanism placing pressure on surplus countries as well as deficit ones. Keynes's central idea. |
| Par value | A currency's declared official rate against the dollar, held within one percent either side. |
| Convertibility commitment | The American promise to exchange dollars for gold at $35 an ounce for foreign central banks. |
| IMF | Created to provide short-term financing so countries could defend a peg while adjusting, rather than deflating or abandoning. |
| Conditionality | The policy changes a borrowing country must accept in return for IMF financing. Contested since 1944. |
Test Your Knowledge
Eight questions. Answer them all before checking the key on the following pages. If a question gives you trouble, the answer key tells you which section to revisit.
- A. Academic economists building a system from theory
- B. Military leaders planning post-war occupation
- C. Practitioners who had lived through the collapse of the 1930s
- D. Private bankers representing commercial interests
- A. A supranational currency with symmetric adjustment pressure on surplus countries
- B. A return to the classical gold standard
- C. Fixing all currencies permanently to the dollar
- D. Allowing all currencies to float freely
- A. It was the more sophisticated design
- B. The other delegations could not understand the bancor
- C. Keynes withdrew his proposal
- D. The United States held the economic power the system required
- A. All currencies would float within agreed bands
- B. The United States would convert dollars to gold at $35 an ounce
- C. Gold would be abolished as a monetary asset
- D. Surplus countries would fund deficit countries
- A. Plus or minus 0.1 percent
- B. There was no band
- C. Plus or minus 5 percent
- D. Plus or minus 1 percent
- A. Borrow and adjust gradually while staying in the system
- B. Devalue without approval
- C. Suspend convertibility temporarily
- D. Convert its reserves into bancor
- A. It was the oldest currency represented
- B. The US held about two thirds of world monetary gold and half its manufacturing
- C. It had never been devalued
- D. The other delegations voted for it
- A. Gold and silver could not both anchor the system
- B. The IMF and World Bank had overlapping mandates
- C. The world needed growing dollar supply, but every dollar had to be gold-convertible
- D. Par values were too narrow to be defended
Answer Key
Each answer explains why the correct choice is correct, why the others are not, and where to reread.
Question 1 · correct answer C
They were policymakers and central bankers who had personally watched the gold standard collapse and the currency wars of the 1930s unfold. That experience shaped every decision.
A describes a theoretical exercise, which this was not. B confuses the monetary conference with wartime planning conducted elsewhere. D is wrong because this was an intergovernmental negotiation.
Review: Section 2, The Brief Was Never Again
Question 2 · correct answer A
The bancor was a new international currency issued by a supranational body, and its most important feature was placing adjustment pressure on surplus countries as well as deficit ones.
B reverses it, since the delegates were designing an alternative to the old standard. C describes White's plan. D describes what eventually replaced Bretton Woods decades later.
Review: Section 3, Two Plans
Question 3 · correct answer D
The United States held about two thirds of world monetary gold and produced roughly half of world manufactured goods. American participation was the prerequisite for any workable system.
A reverses the assessment, since Keynes's design is generally judged the more sophisticated. C is wrong because Keynes argued for his plan and accepted the outcome afterward. B underestimates delegations that understood the proposal perfectly well.
Review: Section 4, Why Keynes Lost
Question 4 · correct answer B
The American promise to convert dollars into gold at a fixed rate for foreign central banks was a legal obligation, and everything else in the system hung off it.
A describes the system that came later. C reverses the design, since gold remained the anchor one step back. D describes Keynes's proposal, which was not adopted.
Review: Section 5, How It Was Built
Question 5 · correct answer D
Currencies were held within one percent either side of their declared par value, maintained through central bank intervention.
A is far tighter than the system required. C is wider than the rules allowed. B is wrong because the band was a defined and central feature.
Review: Section 5, How It Was Built
Question 6 · correct answer A
Short-term financing let a country defend its peg while correcting the underlying problem, instead of choosing between deflation and abandonment.
B is wrong because par value changes required IMF approval. C describes what the gold standard countries did in 1914, not an IMF facility. D refers to a currency that was never created.
Review: Section 6, The Missing Third Option
Question 7 · correct answer B
Every other major economy had spent, lost, or been stripped of its reserves during the war. The dollar was the only currency with the gold and productive capacity to anchor a global system.
A is irrelevant, since age confers nothing here. C is factually wrong, as the dollar's gold value had been changed in the 1930s. D describes a vote that did not decide the matter, since the economics did.
Review: Section 7, Why the Dollar
Question 8 · correct answer C
Growing world trade required a growing supply of dollars held abroad, while the convertibility promise required every dollar to be backed by a fixed quantity of gold. Those requirements pointed in opposite directions.
A describes a nineteenth-century debate that was not the issue here. B describes an institutional question rather than a structural contradiction. D is wrong because the band was defensible, and the flaw sat in the dollar-gold link itself.
Review: Section 8, The Flaw in the Foundation
Keep going
Where Money Came From is written by Kanin D. Alldredge for The Currency Classroom, and it is free to read. There is more free from CNS: start here.
Start free with CNS →