Crypto and Currency

1The Test Already Exists
Lesson 29 asked what money actually is. The answer was that it is not defined by what it is made of. Shells, salt, grain, silver, and entries in a database have all been money.
What they had in common was doing three jobs at once.
| The Job | The Test |
|---|---|
| Medium of exchange | Can you spend it? |
| Store of value | Will it still be worth something later? |
| Unit of account | Are prices written in it? |
That test was built for currencies and it applies to anything claiming to be money. So apply it.
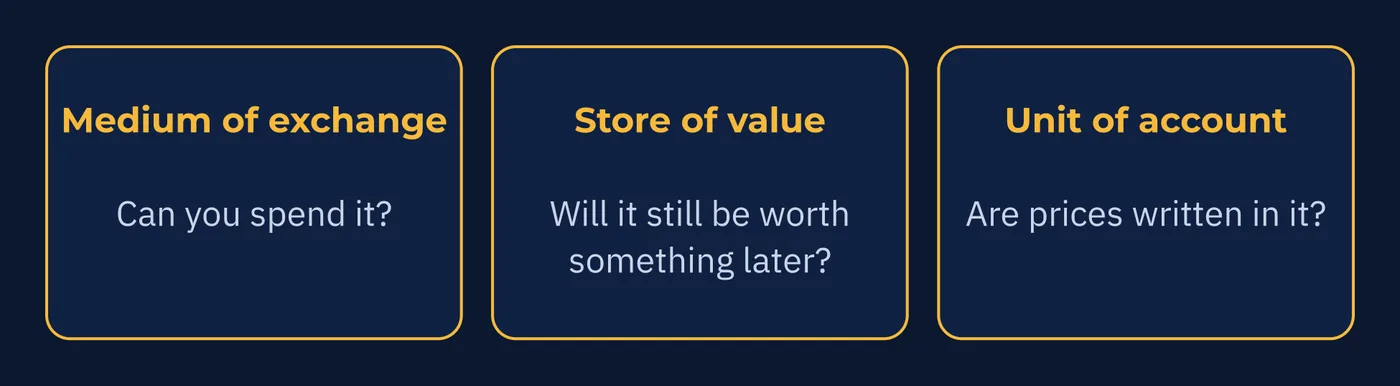
The discipline here is answering each question on its own, rather than reaching for a verdict. Crypto scores very differently on the three, and that pattern says more than any summary.
2Can You Spend It?
Partly, and more than most skeptics allow.
Bitcoin can be sent to anyone with a connection. No permission, any hour, across any border. For some payments that is genuinely useful, especially where the usual arrangements are slow, expensive, or unavailable.
But acceptance stays narrow. Most businesses do not take it. Most people have never bought anything with it. El Salvador made it legal tender in 2021, which tested whether adoption follows from a legal requirement. In early 2025 it amended the law so businesses no longer have to accept it. The evidence there is mixed rather than decisive.
There is also a problem the technology cannot fix, and it comes from the next test.
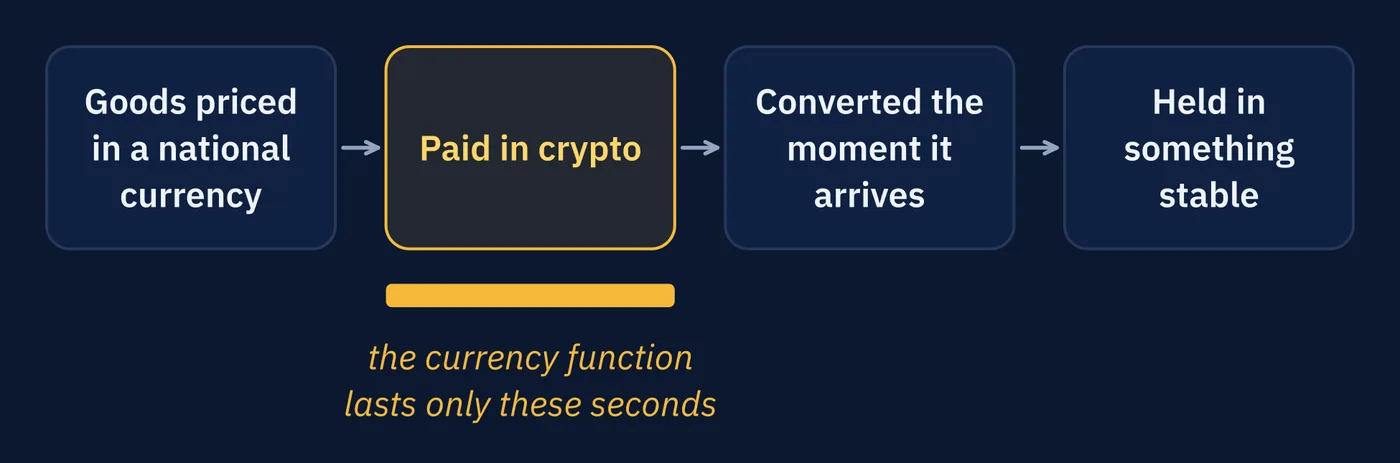
A partial pass, then. Real capability, limited acceptance, and an obstacle that comes from elsewhere.
3Will It Hold Its Value?
This is the contested one, and it deserves the argument on both sides rather than a verdict.
The case in favor rests on properties that are real and checkable. A supply fixed at twenty-one million, with no mechanism to change it. Enforcement spread across thousands of independent participants rather than resting on an institution. More than fifteen years of continuous operation and growing adoption.
Set against Lesson 30, that argument has force. Every fiat currency is designed to lose purchasing power, halving in roughly thirty-five years at a two percent target. A fixed supply answers that directly.
The case against is equally concrete.
| The Objection | Why It Bites |
|---|---|
| Short-term volatility | Moves of 40 to 80 percent within single years. Gold and government bonds do not behave that way, and they are the comparison being invited. |
| Behavior under stress | During the 2022 tightening cycle it moved with risk assets rather than against them, which is the opposite of what a safe haven does. |
| A short record | More than fifteen years is long for a technology and brief for a claim about holding value across decades. |
It may be a store of value over decades. It is demonstrably not one over months.
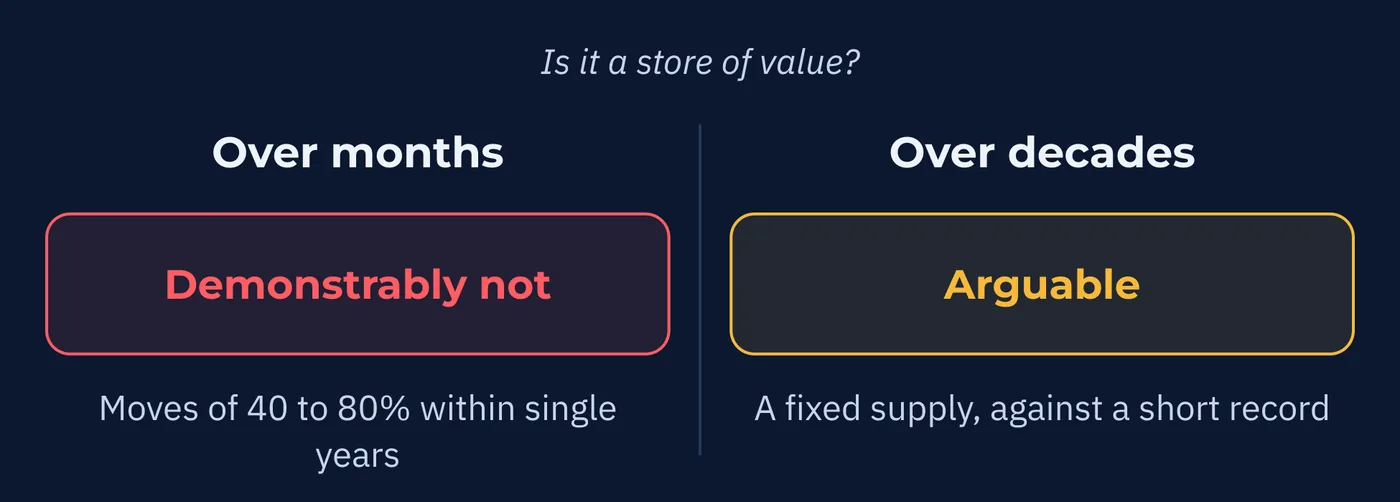
Both halves of that sentence matter. Anyone asserting only the first is selling something. Anyone asserting only the second has not engaged with the supply argument.
4Are Prices Written In It?
The third test is the one usually skipped, and it produces the clearest answer of the three.
Almost nothing in the world is priced in Bitcoin. Not wages, not rents. Goods you can buy with it are almost always priced in a national currency and converted at the moment of payment.
But the decisive evidence is not out in the wider economy. It sits inside the crypto market itself.
The crypto market prices itself in dollars.
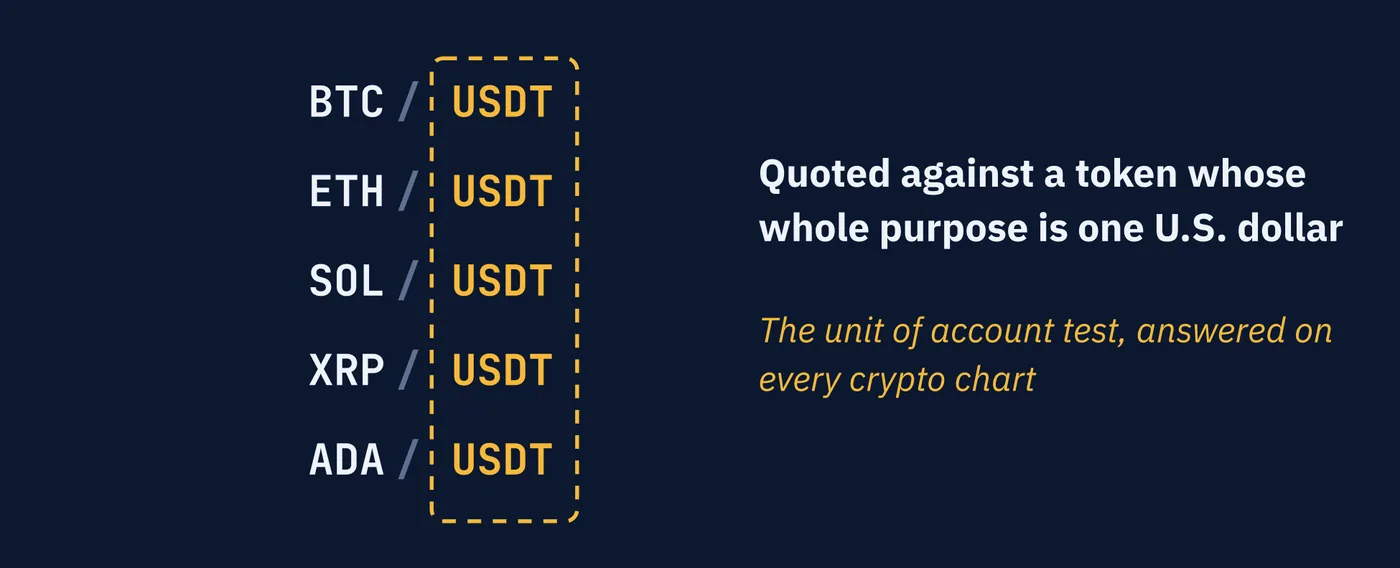
Lesson 50 established that most crypto prices are quoted against a dollar stablecoin. Not against Bitcoin. Not against each other. Against a token whose whole purpose is to represent one U.S. dollar.
Which is remarkable once you notice it. An asset class built partly as an alternative to the dollar has adopted the dollar as its unit of account. Voluntarily, because pricing in something that moves is impractical.
On this test the answer is not partial. It is a clear fail, and the evidence is on every crypto chart anyone has ever looked at.
5The Scorecard
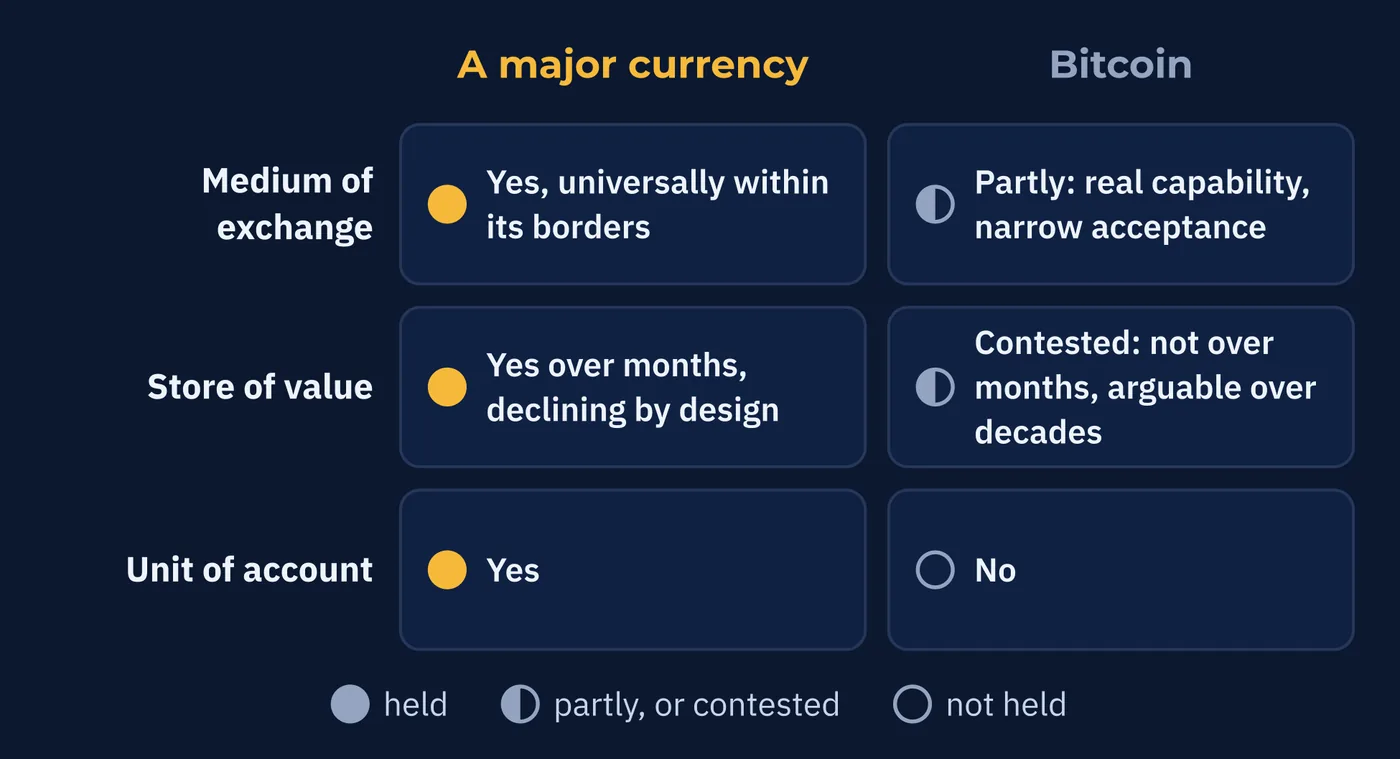
| Test | A Major Currency | Bitcoin |
|---|---|---|
| Medium of exchange | Yes, universally within its borders | Partly. Real capability, narrow acceptance. |
| Store of value | Yes over months, declining slowly by design | Contested. Not over months. Arguable over decades. |
| Unit of account | Yes | No |
Lesson 29 described how a currency fails, and the order matters. Store of value goes first. Medium of exchange second. Unit of account last, and that one is the clearest sign of collapse.
Bitcoin's pattern is reversed. It has never held the unit of account function. It holds medium of exchange partially. And it contests store of value most strongly of the three.
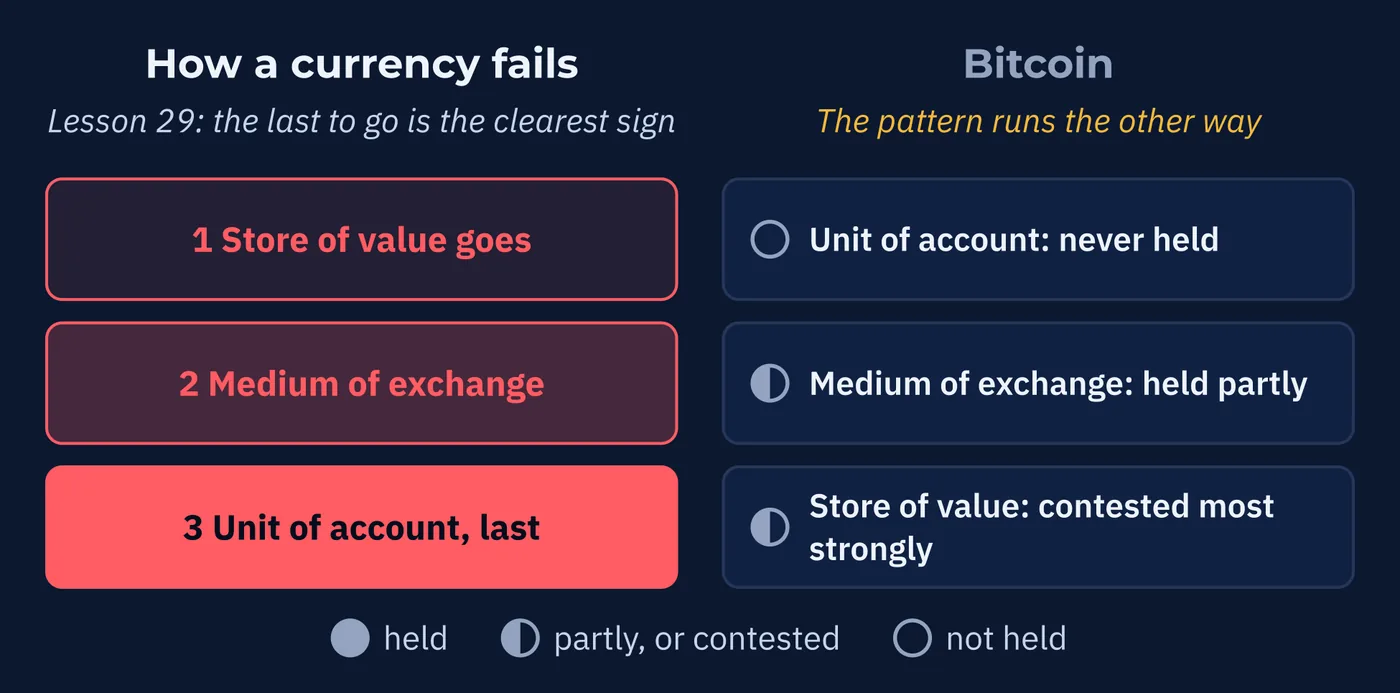
Which suggests something worth saying plainly. Bitcoin is not a currency that is failing. It is something else, described using the vocabulary of currency, and the vocabulary fits badly.
6What It Might Actually Be
Several descriptions fit better than currency, and each has a constituency.
| Description | What It Captures | Where It Strains |
|---|---|---|
| Digital gold | Scarcity, no issuer, a hedge against currency debasement | Gold is far less volatile and has thousands of years of record |
| A risk asset | Its actual observed behavior, moving with appetite for risk | Sits awkwardly beside the debasement hedge argument |
| A payment network | The capability is genuine and permissionless | Understates what most holders are actually doing with it |
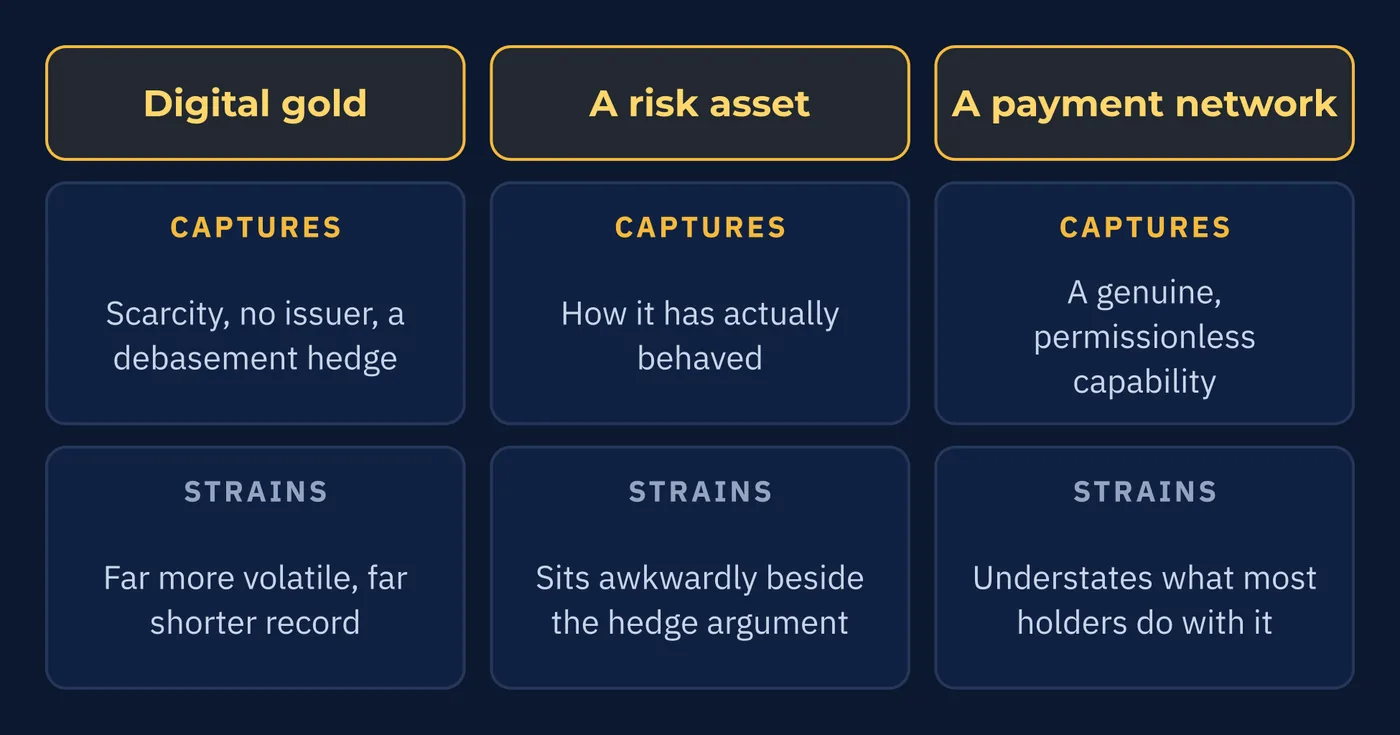
The second row is worth studying. It is where observation and argument pull against each other.
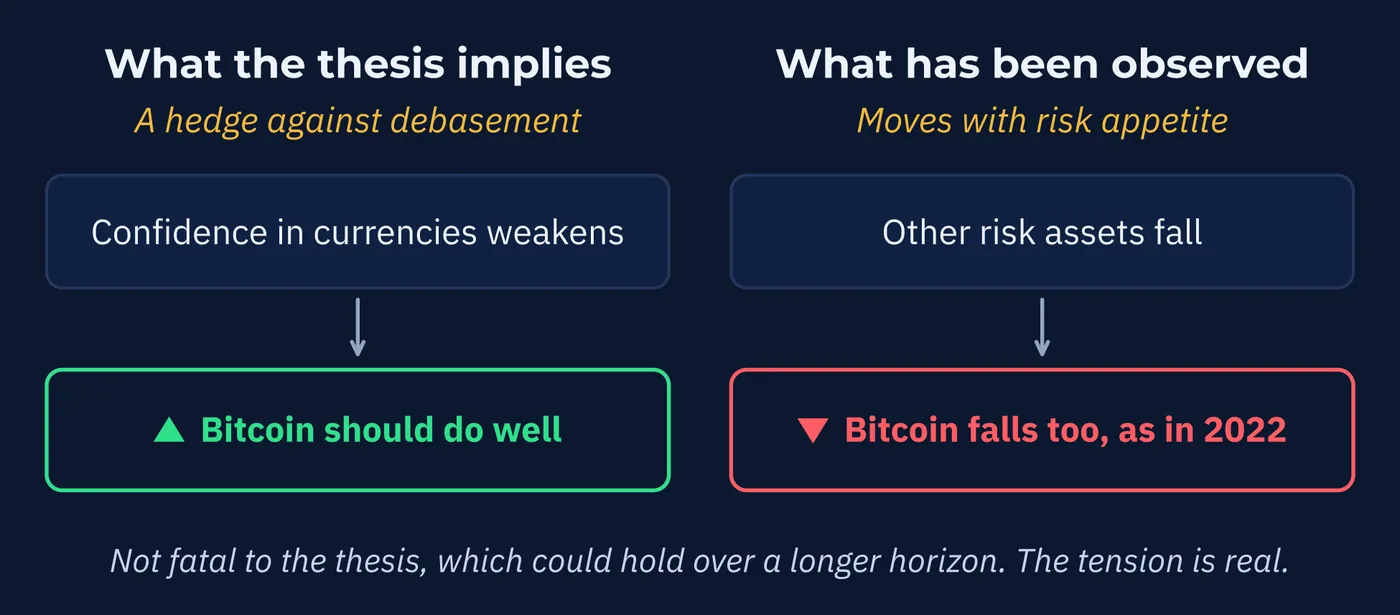
The case for Bitcoin is largely a case about currency debasement. That implies it should do well when confidence in currencies weakens. Its observed behavior has been to move with risk appetite, falling when other risk assets fall. Lesson 46 noted that holding it alongside a commodity currency is one bet, not two.
Those two things are in tension. Not fatally, since a thesis can be right on a longer horizon than the observations so far. But the tension is real.
7Both Cases, Stated Fairly
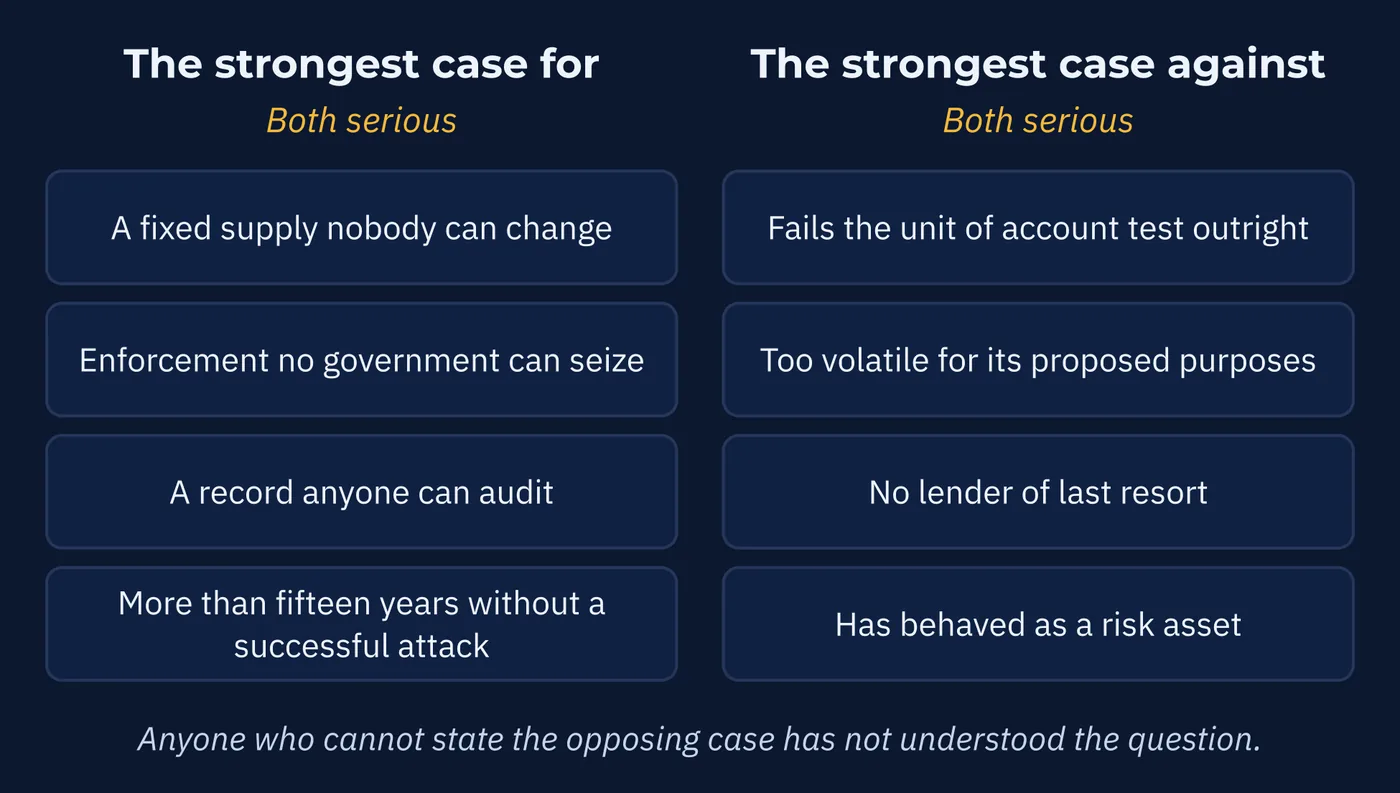
What you should take from this series is not a position. It is the ability to hear either case, know which parts are evidence and which are assertion, and recognize which of those arguments should matter to you when deciding how, when, or whether to trade it.
8What These Fifty-One Lessons Were For
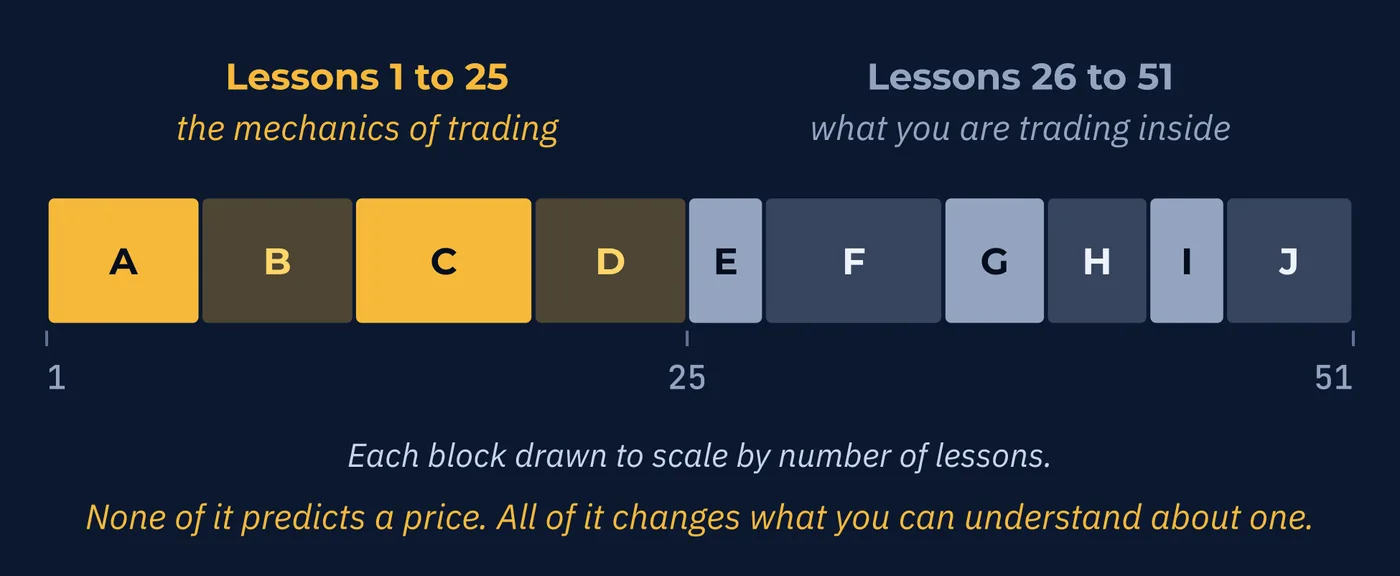
In Lesson 26, the question was: what are you actually doing when you open a position? This lesson closes that loop. The path between those two points was deliberate.
| Series | What It Established |
|---|---|
| What You Are Actually Doing | The category is set by you, not the market. An edge is tested, not read about. |
| Where Money Came From | Money is trust with four pillars, most of it lent into existence, and every monetary commitment can be withdrawn. |
| The Dollar's Position | A historical outcome rather than a permanent feature, with real costs on both sides. |
| The Market Today | No center, no official price, and almost nobody in it trying to beat you. |
| How Markets Move Together | Diversification is ideas, not positions. |
| Crypto From First Principles | An answer to Series F, understood using the tools Series F provided. |
The first twenty-five lessons taught the mechanics of trading. What a pip is, what a trade costs, how much to risk, when to be at the screen.
The twenty-six that followed taught context. Not how to place a trade, but what you are placing it inside.
None of it predicts a price. All of it changes what you can understand about one.
Consider a trader who knows four things. That the dollar sits in most pairs because of decisions taken in 1944 and 1971. That most market volume is not speculation. That a flat line usually means a commitment rather than calm. And that a stablecoin is a peg, subject to the same five failures as any other. They are reading the same chart as everyone else and seeing considerably more in it.
That is what fifty-one lessons buy. Not certainty about what happens next, which nobody has. A better understanding of what you are looking at. Your strategy may be technical, fundamental, systematic, discretionary, short term, or long term. The method can change. A deeper understanding of the market gives you more context for the decisions that method asks you to make.
Three Things to Remember
Try This
Twenty minutes. The last step is the one that matters most.
Words From This Lesson
| Term | What It Means |
|---|---|
| Medium of exchange | Money's function as something people accept in return for goods and services. |
| Store of value | Money's function as something that holds worth over time. |
| Unit of account | Money's function as the measure prices are written in. The test crypto fails most clearly. |
| Digital gold | A description of Bitcoin emphasizing scarcity and absence of an issuer. |
| Risk asset | An asset that strengthens when appetite for risk is high. Bitcoin's observed behavior so far. |
| Debasement | The loss of a currency's purchasing power. The problem the fixed supply argument addresses. |
Test Your Knowledge
Eight questions. Answer them all before checking the key on the following pages. If a question gives you trouble, the answer key tells you which section to revisit.
- A. Scarcity, portability, durability
- B. Medium of exchange, store of value, unit of account
- C. Issuance, circulation, redemption
- D. Liquidity, volatility, acceptance
- A. It fails completely
- B. As well as any national currency
- C. Partly. Real capability, but narrow acceptance
- D. Only in countries where it is legal tender
- A. A merchant cannot price goods in something that moves 10 percent in a day
- B. Transactions take longer to confirm
- C. Fees rise with volatility
- D. Networks halt during volatile periods
- A. It acted as a safe haven, as predicted
- B. It held a stable value throughout
- C. It was uncorrelated with everything
- D. It moved with risk assets, contradicting safe haven expectations
- A. Medium of exchange
- B. Store of value
- C. Unit of account
- D. It passes all three
- A. Few shops accept Bitcoin
- B. Governments do not recognize it
- C. Wages are not paid in Bitcoin
- D. The crypto market itself quotes prices against dollar stablecoins
- A. It is identical
- B. A currency loses store of value first and unit of account last. Bitcoin never held unit of account at all.
- C. Bitcoin fails faster
- D. Bitcoin fails only during recessions
- A. The case is about currency debasement, but it has behaved as a risk asset
- B. None, the two align closely
- C. Its supply is not actually fixed
- D. It has never been tested under stress
Answer Key
Each answer explains why the correct choice is correct, why the others are not, and where to reread.
Question 1 · correct answer B
Lesson 29 established that money is defined by what it does. It must be accepted in exchange, hold worth over time, and serve as the measure prices are written in.
A lists useful properties that support the functions without being them. C describes how currency is issued and managed. D lists market characteristics rather than monetary functions.
Review: Section 1, The Test Already Exists
Question 2 · correct answer C
It can be sent to anyone, anywhere, without permission, which is genuinely useful. But most businesses do not accept it and most people have never spent it.
A dismisses a real capability. B overstates acceptance considerably. D is too narrow, since it is used in many places without legal tender status.
Review: Section 2, Can You Spend It?
Question 3 · correct answer A
A merchant must either reprice constantly, absorb the risk, or convert immediately on receipt. Most choose the third, which means the currency function lasts only seconds.
B describes a technical property unrelated to pricing. C conflates network congestion with price movement. D is wrong because networks continue operating through volatility.
Review: Section 2, Can You Spend It?
Question 4 · correct answer D
It fell alongside other risk assets rather than strengthening as stress rose, which is the opposite of safe haven behavior and a direct challenge to part of the case for it.
A states what some expected and not what happened. C is wrong because a clear correlation with risk assets was observable. B contradicts the recorded price movement.
Review: Section 3, Will It Hold Its Value?
Question 5 · correct answer C
Almost nothing is priced in Bitcoin. The other two tests produce partial or contested results, but this one produces a clear negative.
A is a partial pass with real capability behind it. B is genuinely contested, with serious arguments on both sides. D overstates its performance on every test.
Review: Section 4, Are Prices Written In It?
Question 6 · correct answer D
Most crypto prices are quoted against a dollar stablecoin. An asset class positioned partly as an alternative to the dollar has adopted the dollar as its unit of account.
A, C, and B are all true and all weaker, because they describe the outside world. The strongest evidence comes from inside the crypto market itself.
Review: Section 4, Are Prices Written In It?
Question 7 · correct answer B
Lesson 29 described failure running from store of value through medium of exchange to unit of account. Bitcoin's pattern is reversed, which suggests it is not a currency failing but something else.
A ignores a clear structural difference. C describes speed rather than pattern. D invents a condition unrelated to the functions.
Review: Section 5, The Scorecard
Question 8 · correct answer A
A hedge against currency debasement should perform well when confidence in currencies weakens. Its observed behavior has been to fall alongside other risk assets instead.
B denies a tension the evidence supports. C is factually wrong, since the supply cap is enforced in code. D is wrong because it has traded through several significant stress episodes.
Review: Section 6, What It Might Actually Be
Keep going
Crypto From First Principles is written by Kanin D. Alldredge for The Currency Classroom, and it is free to read. There is more free from CNS: start here.
Start free with CNS →