Stablecoins, Properly

1The Half Nobody Examines
Lesson 2 established that every price has two currencies in it. Lesson 11 pointed out that most crypto prices are quoted against a stablecoin, not against actual dollars.
So a trader looking at a crypto price studies one half of it carefully and ignores the other.
If the quote currency moves, the price moves, whatever the asset did.
A stablecoin is designed to hold a fixed value, almost always one US dollar. When it does, it is invisible. When it does not, every price quoted against it moves at once.
So it is worth knowing what is actually holding that dollar in place.
2Three Different Promises
There are three ways to make a token worth a dollar. They have almost nothing in common except the result they aim at.
| Type | How the Dollar Is Held | Example |
|---|---|---|
| Fiat-backed | Real dollars or dollar assets held in reserve, one for one | USDT, USDC |
| Crypto-backed | More than a dollar of volatile crypto locked as collateral | DAI (now alongside USDS) |
| Algorithmic | Nothing held. Code adjusts supply to push the price back | TerraUSD, formerly |
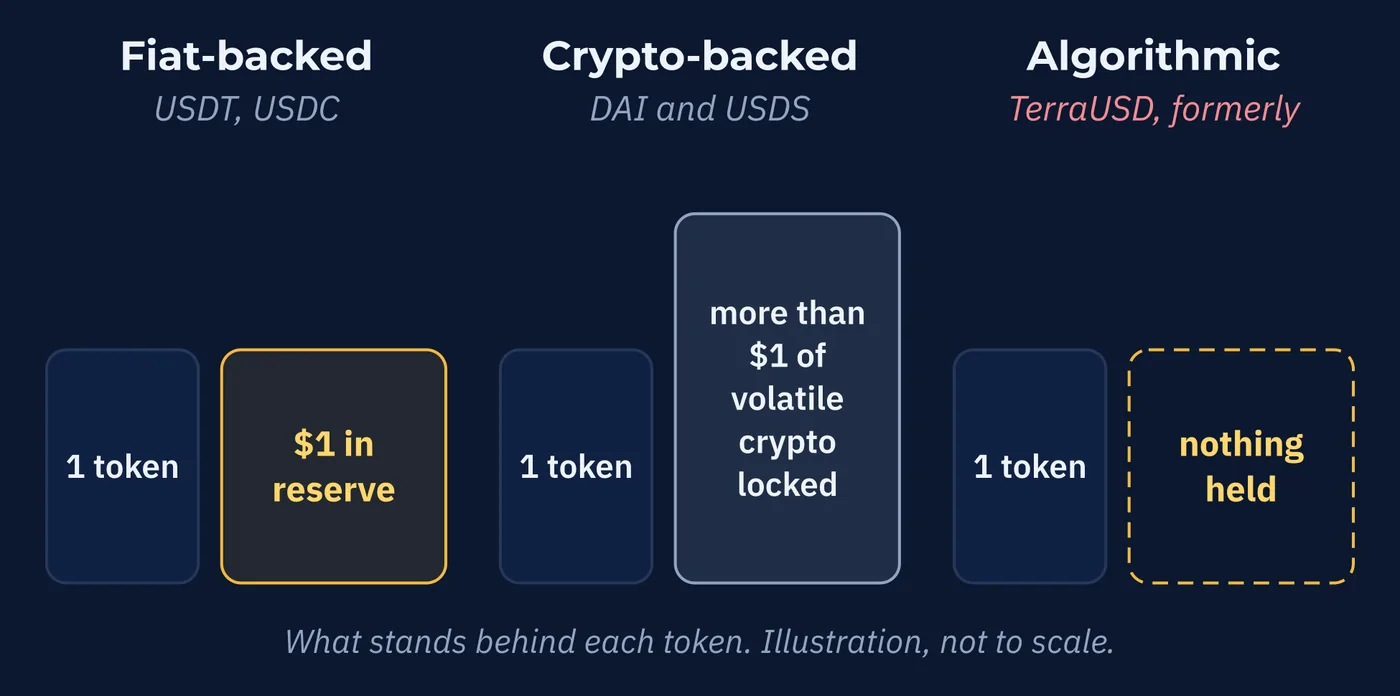
Lesson 34 gave the framework for these. A fiat-backed stablecoin is a currency board. The mechanism holds reserves against every unit issued. An algorithmic one is a promise resting on belief, with no reserve underneath.
Lesson 34 also explained why that difference is not a matter of degree. A currency board removes the decision point. A promise still has one.
3Three Different Ways to Break
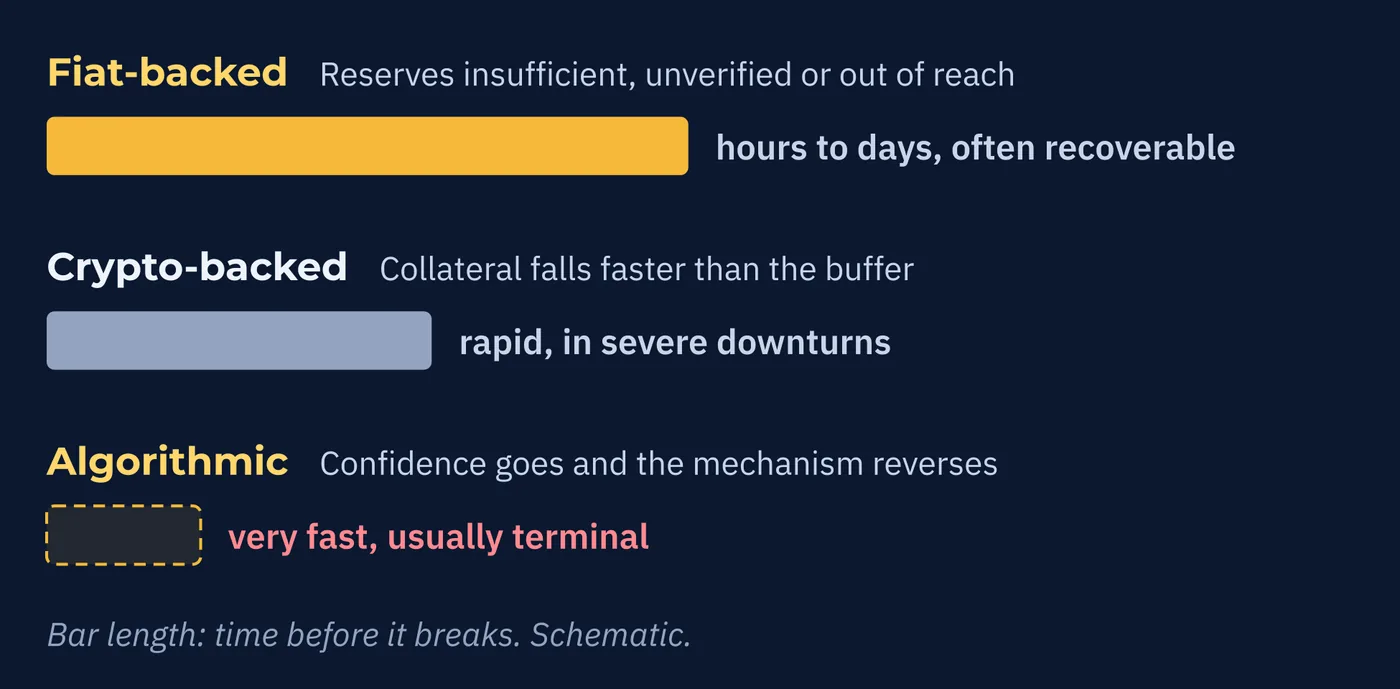
Because the backing differs, the failure differs. That is the practical reason to know which type you hold.
| Type | How It Fails | How Fast |
|---|---|---|
| Fiat-backed | Reserves are insufficient, unverified, or inaccessible when needed | Hours to days, and often recoverable |
| Crypto-backed | Collateral falls faster than the buffer absorbs, and forced selling amplifies the fall | Rapid, during severe downturns |
| Algorithmic | Confidence goes, and the restoring mechanism reverses into a spiral | Very fast, and usually terminal |
Read the third row carefully, because it contains something dangerous.
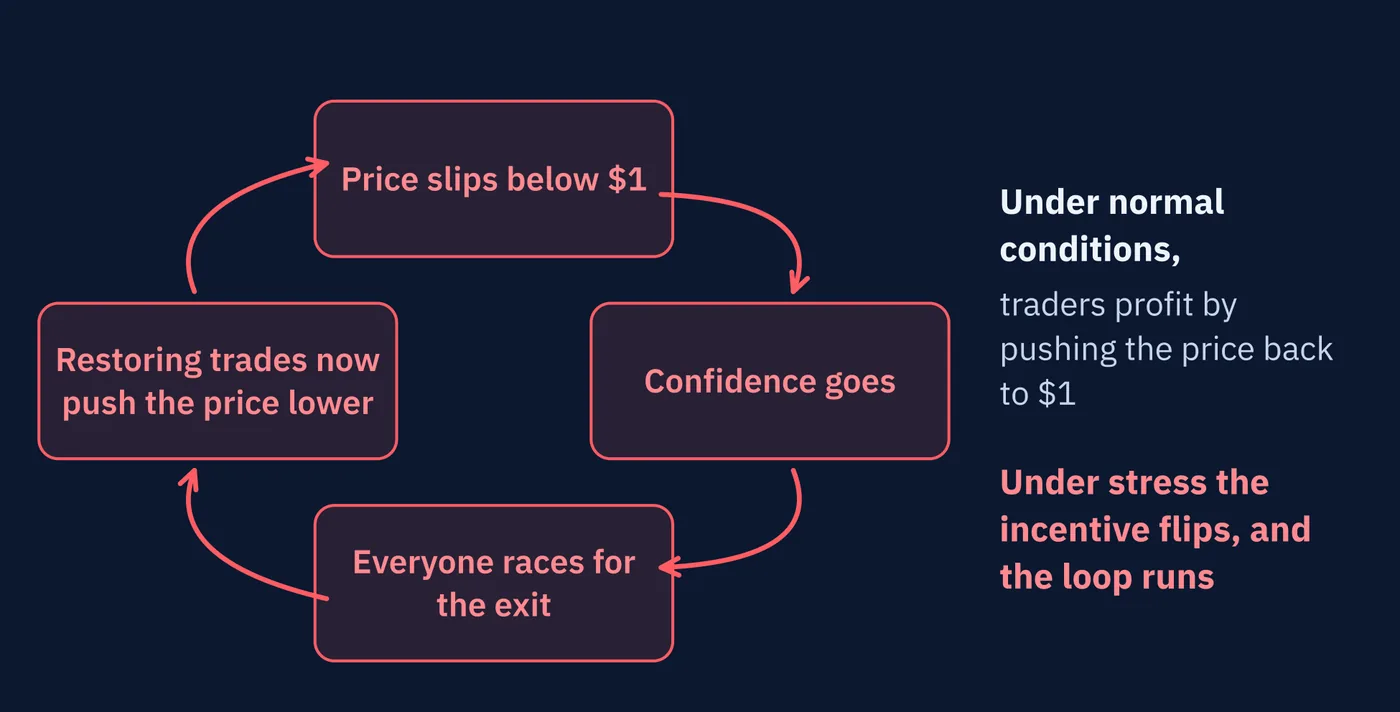
An algorithmic stablecoin relies on participants having a profitable reason to trade the price back toward a dollar whenever it drifts. Under normal conditions that works. Under stress, when everyone wants out at once, the incentive flips. Participants race for the exit instead. The mechanism built to restore stability accelerates the collapse.
The repair mechanism becomes the demolition mechanism.
4A Peg That Bent and Recovered
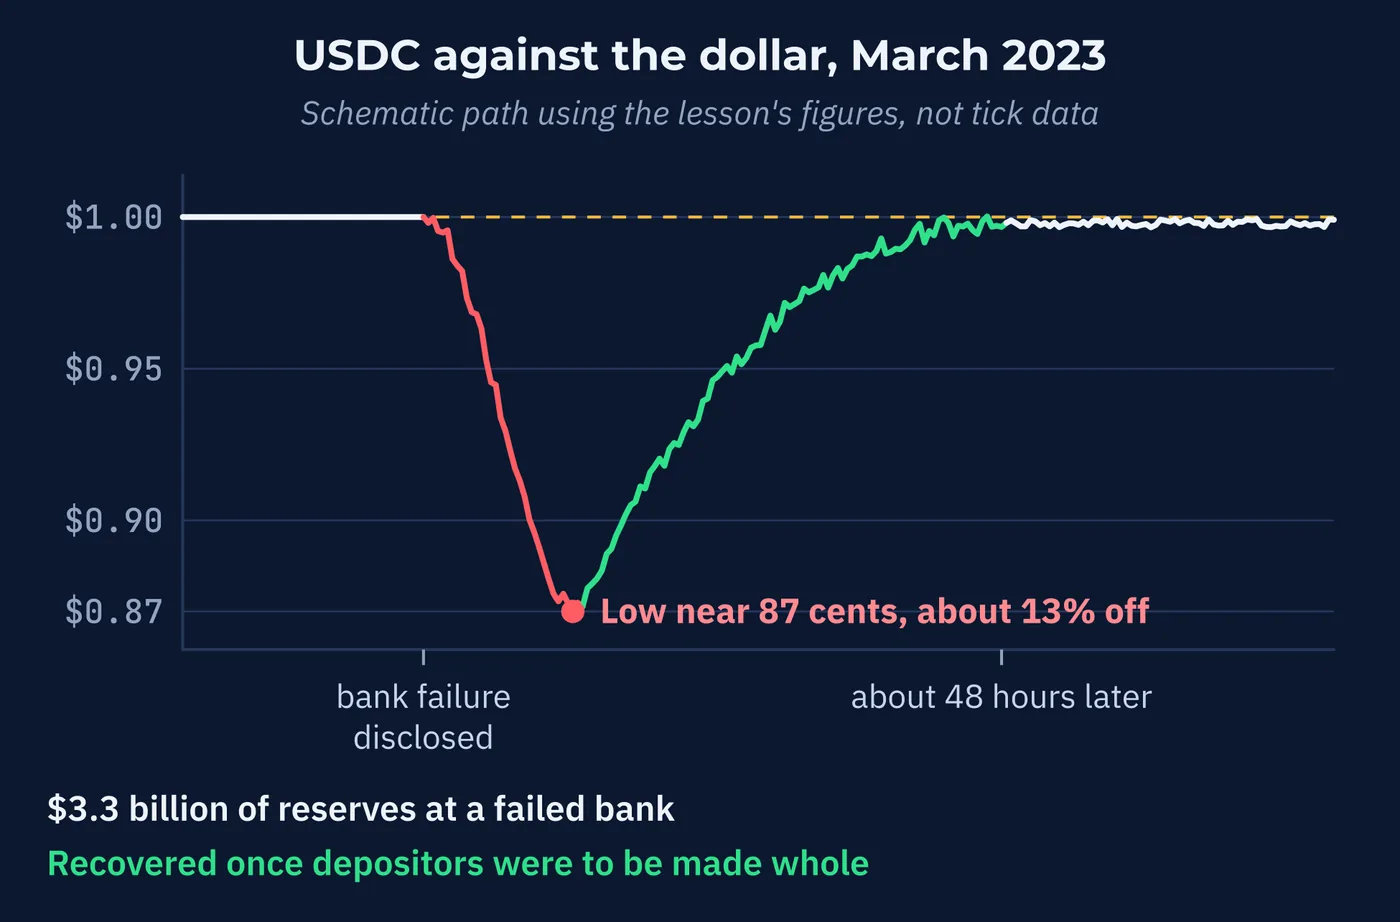
In March 2023 a major fiat-backed stablecoin, USDC, briefly lost its dollar.
Its issuer disclosed that 3.3 billion dollars of reserves sat at a bank that had just failed. The token traded as low as about eighty-seven cents. A discount of roughly thirteen percent.
The important detail is what the concern actually was.
| The Worry Was Not | The Worry Was |
|---|---|
| That the reserves did not exist | Whether they could be reached |
| That the issuer had lied | Whether redemptions would function during the bank's failure |
When authorities confirmed the bank's depositors would be made whole, confidence returned. The peg recovered fully within about forty-eight hours.
5A Peg That Did Not Recover
In May 2022 an algorithmic stablecoin failed completely. Roughly forty billion dollars of combined value was destroyed in a matter of days.
There was no reserve to deploy. Only the mechanism. Once confidence went, it worked in reverse, exactly as Section 3 describes.
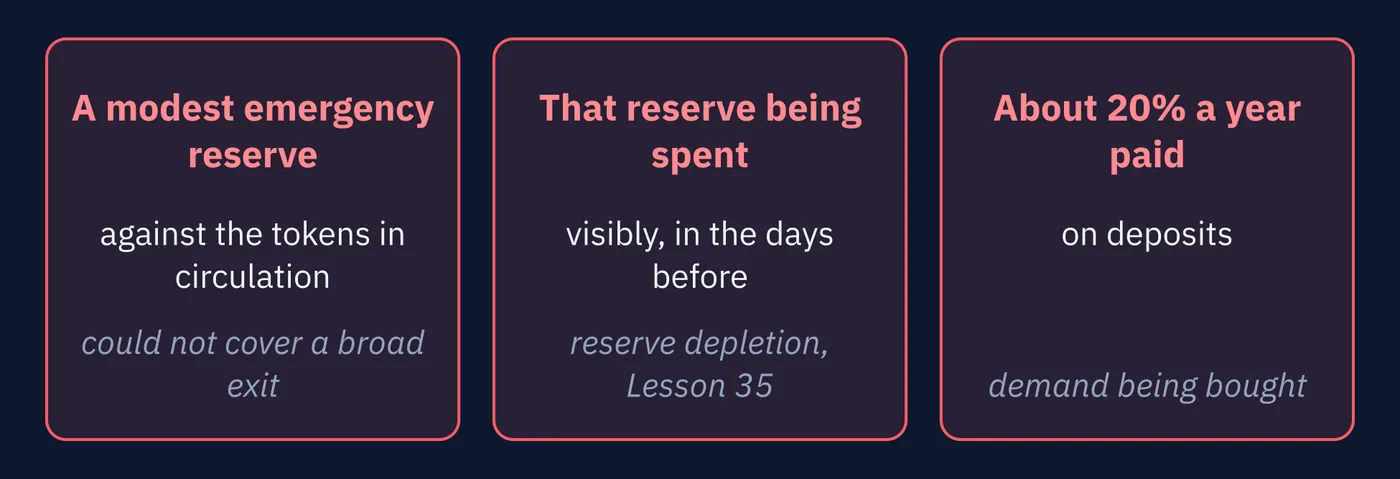
What makes this worth studying rather than just noting is that the stress was visible in advance.
| The Signal | What It Meant |
|---|---|
| The emergency reserve was modest against the tokens in circulation | The backstop could not have covered a broad exit |
| That reserve was being spent, visibly, in the days before | Lesson 35 called reserve depletion the first mechanism, and it was observable |
| Deposits were being paid about 20 percent a year | The demand holding the system together was being bought |
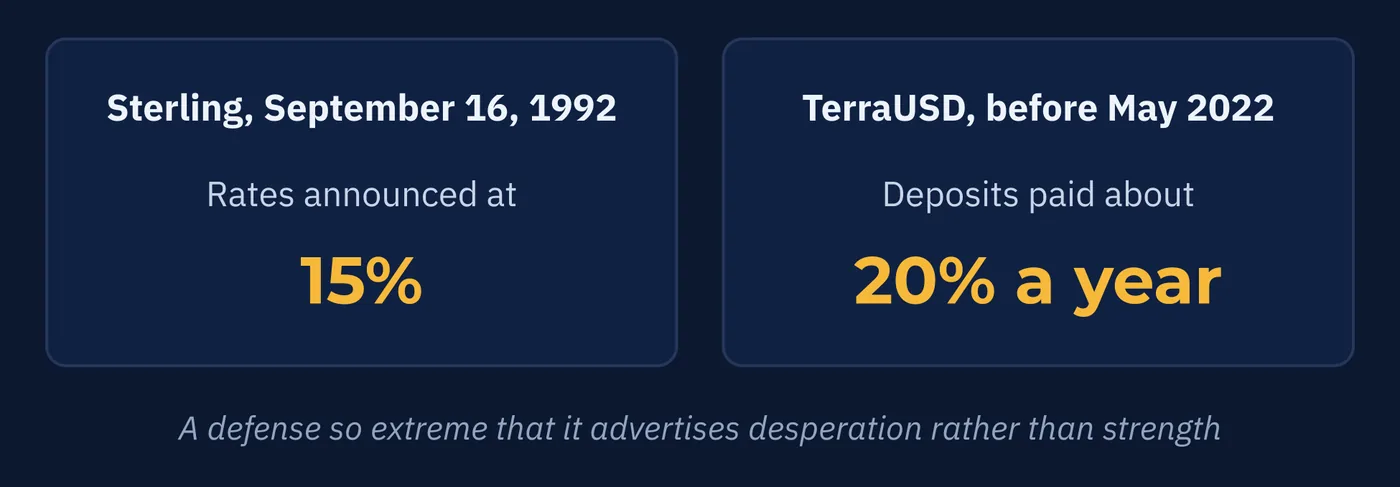
The last row deserves the comparison it invites.
Lesson 35 described the Bank of England raising rates toward fifteen percent in one day to defend sterling. The defense failed partly because it was so extreme that nobody believed it could last. The attempt advertised desperation rather than strength.
A protocol paying twenty percent a year to hold its peg is that same signal, in a different alphabet.
6The Framework Transfers Exactly
Which is the deeper point of this lesson. It is also why the lesson sits here in the course rather than the beginning.
Lesson 35 listed five ways a currency peg breaks. Every one has a stablecoin equivalent.
| From Lesson 35 | In a Stablecoin |
|---|---|
| Reserve depletion | The backstop being spent, visibly, before the break |
| Fundamental misalignment | A promise the backing cannot actually support |
| Speculative attack | Coordinated selling that starts the confidence break |
| Voluntary abandonment | An issuer choosing to stop defending the price |
| Credibility withdrawal | Belief going, after which nothing else matters |
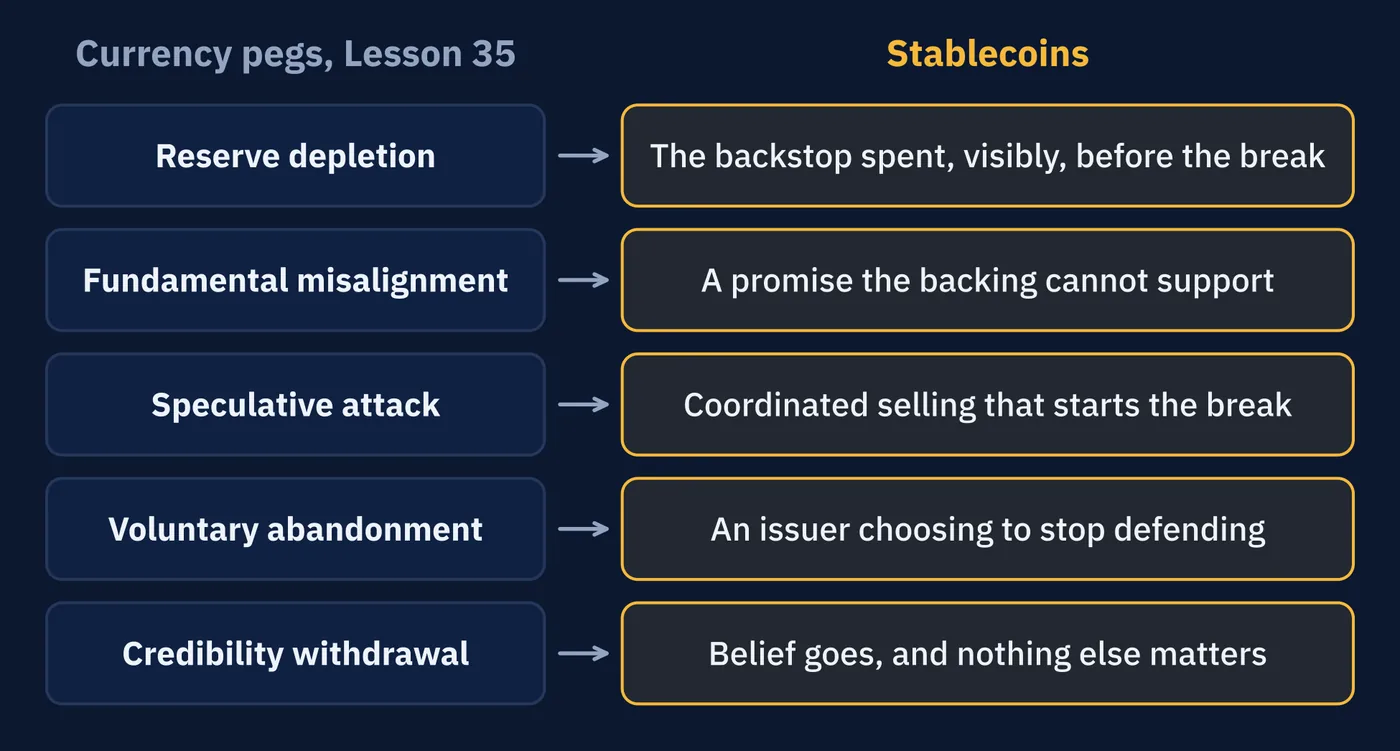
Nothing in that table needed new knowledge. A trader who understood why sterling broke in 1992, and why the Swiss floor was withdrawn in 2015, already had the tools to assess a stablecoin.
Which says something about how this course has been built. Pattern recognition across asset classes is worth something on its own. Treating crypto as a separate universe throws away everything Series F established.
7What This Means Practically
Two consequences follow for anyone holding or quoting in a stablecoin.
The first is that the type matters more than the name. All three are called stablecoins. Treating them as equivalent because they share a label is the same error as treating all currency pegs as equally credible because they are all called pegs.
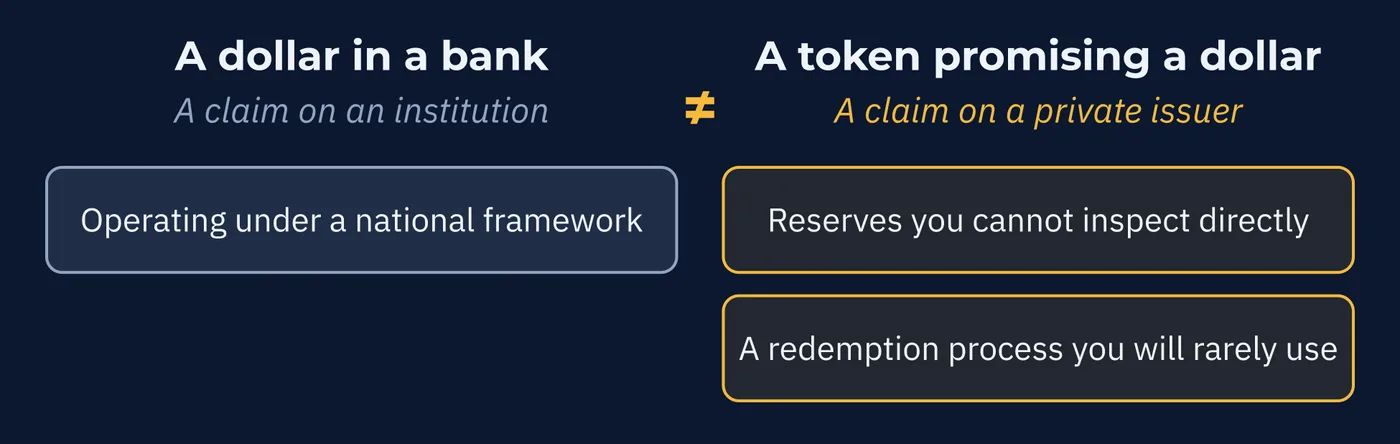
The second concerns what you actually hold. Lesson 11 made the point briefly. It is worth restating now that the mechanics are in place.
a dollar in a bank ≠ a token promising a dollarOne is a claim on an institution operating under a national framework. The other is a claim on a private issuer. Its ability to honor that claim depends on reserves you cannot inspect directly, and a redemption process you will probably never use.
That is not an argument against using them. They serve a real function, and crypto trading would be far more awkward without them. It is an argument for knowing which of the three you hold.
8Biggest Is Not Most Transparent
One factual point remains, and it matters because most people assume the two go together.
The most widely used stablecoin and the most transparent one are not the same asset.
| USDC | USDT | |
|---|---|---|
| Reserve disclosures | Weekly, with monthly third-party attestation | Quarterly attestation |
| Full independent audit | Yes, annually since 2018, within Circle's audited financial statements | First completed August 2026 (KPMG, for 2025) |
| Market position | Smaller | The largest, and the dominant quote currency |
The next lesson closes the series. It sets crypto and currency side by side against the three functions of money from Lesson 29, and asks honestly which tests each one passes.
Three Things to Remember
Try This
Fifteen minutes. Two of these you can check in a browser.
Words From This Lesson
| Term | What It Means |
|---|---|
| Stablecoin | A token designed to hold a fixed value, almost always one US dollar. |
| Fiat-backed | Backed by reserves of real dollars or dollar assets, one for one. A currency board analog. |
| Crypto-backed | Backed by more than a dollar of volatile crypto locked as collateral. |
| Algorithmic | Backed by nothing. Code adjusts supply to push the price toward the peg. |
| De-peg | A loss of the fixed value the token was designed to hold. |
| Attestation | A third-party report on reserves. Less thorough than a full independent audit. |
| Liquidation cascade | Forced selling of collateral that pushes prices lower, triggering further forced selling. |
Test Your Knowledge
Eight questions. Answer them all before checking the key on the following pages. If a question gives you trouble, the answer key tells you which section to revisit.
- A. It determines the trading hours
- B. If it moves, the price moves regardless of what the asset did
- C. It sets the spread
- D. It has no effect on the quote
- A. Code adjusts the supply automatically
- B. Over-collateralization with crypto
- C. Real dollars or dollar assets held in reserve
- D. A government guarantee
- A. Collateral falling faster than the buffer absorbs, with forced selling amplifying it
- B. Reserve opacity
- C. Confidence collapse in a code mechanism
- D. Regulatory prohibition
- A. It restores the peg more aggressively
- B. It pauses automatically
- C. The incentives reverse and it accelerates the collapse
- D. It converts to fiat backing
- A. The reserves did not exist
- B. The blockchain had failed
- C. The issuer had committed fraud
- D. Whether the reserves could be accessed during a bank failure
- A. Fixed supply, mining, and consensus
- B. Low volatility, high volume, and regulation
- C. Government backing, audits, and insurance
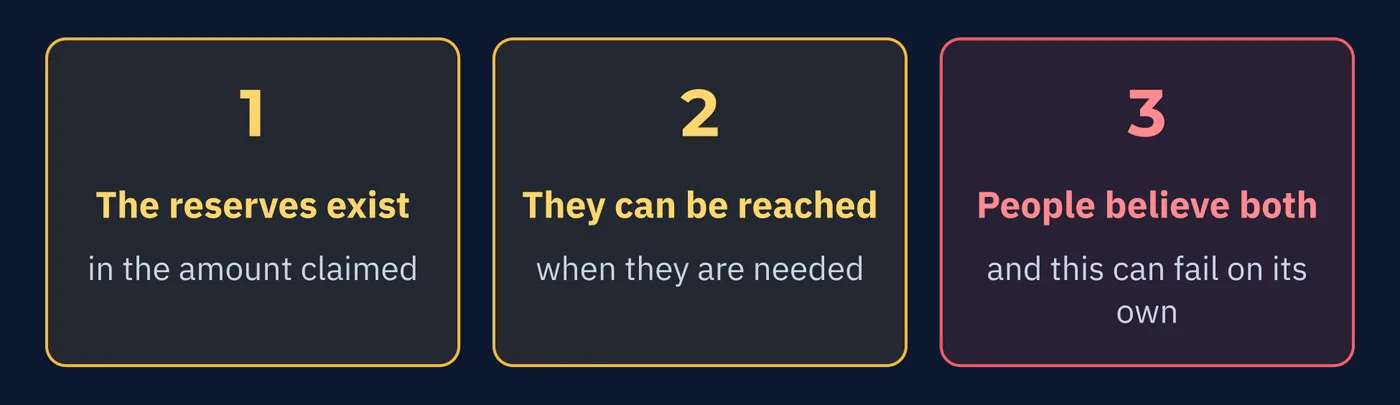
- D. Reserves exist, are accessible, and are believed in
- A. An unsustainable interest rate defense of a peg
- B. A currency board arrangement
- C. Normal money market returns
- D. A central bank swap agreement
- A. It is also the most transparent
- B. It is not the most transparent, and had not completed a full independent audit as of early 2026
- C. It is fully audited monthly by regulators
- D. It is algorithmic
Answer Key
Each answer explains why the correct choice is correct, why the others are not, and where to reread.
Question 1 · correct answer B
Every price has two currencies in it. Most crypto prices are quoted against a stablecoin, so if that stablecoin loses its value the price changes whatever the asset did.
A is unrelated, since crypto markets run continuously. C describes a cost that exists independently of the quote currency's stability. D is the assumption this lesson exists to correct.
Review: Section 1, The Half Nobody Examines
Question 2 · correct answer C
Reserves of actual dollars or dollar-denominated assets are held against every token issued, which makes it a currency board analog in Lesson 34's terms.
A describes an algorithmic stablecoin. B describes a crypto-backed one. D is wrong because no government guarantees these tokens.
Review: Section 2, Three Different Promises
Question 3 · correct answer A
The collateral is volatile. In a severe downturn it can fall faster than the over-collateralization buffer absorbs, and the liquidation designed to protect the peg adds to the selling.
B is the fiat-backed failure mode. C is the algorithmic one. D describes an external event rather than a structural weakness.
Review: Section 3, Three Different Ways to Break
Question 4 · correct answer C
The design assumes participants have a profitable reason to trade the price back toward a dollar. Under stress that incentive flips and everyone races for the exit instead.
A describes what the design intends and not what happens under stress. B invents a pause that does not exist. D is wrong because no such conversion is possible.
Review: Section 3, Three Different Ways to Break
Question 5 · correct answer D
Reserves of 3.3 billion dollars were held at a bank that had just failed. The question was accessibility during the resolution, not existence, and the peg recovered once deposits were guaranteed.
A and C both misstate the situation, since the reserves were real and disclosed. B is wrong because no technical failure was involved.
Review: Section 4, A Peg That Bent and Recovered
Question 6 · correct answer D
The reserves must exist in the amount claimed, be reachable when needed, and be believed in by participants. The third can fail on its own.
B lists market characteristics rather than peg requirements. C describes protections these tokens do not carry. A describes blockchain mechanics from Lesson 48.
Review: Section 4, A Peg That Bent and Recovered
Question 7 · correct answer A
Paying an extraordinary rate to hold demand in place is the same signal as raising interest rates to an unsustainable level to defend a currency. The defense advertises the difficulty.
B describes a mechanism with reserves behind it, which is the opposite arrangement. C badly understates a rate far above ordinary returns. D describes an arrangement between central banks.
Review: Section 5, A Peg That Did Not Recover
Question 8 · correct answer B
The most widely used and the most transparent are not the same asset. As of early 2026 the largest published quarterly attestations but had not completed a full independent audit. Its first, by KPMG, was announced in August 2026.
A is the common assumption and it is incorrect. C overstates the current requirements, though legislation from July 2025 moves in that direction. D is wrong because the largest is fiat-backed.
Review: Section 8, Biggest Is Not Most Transparent
Keep going
Crypto From First Principles is written by Kanin D. Alldredge for The Currency Classroom, and it is free to read. There is more free from CNS: start here.
Start free with CNS →