Beyond Bitcoin

1Deliberately Limited
Bitcoin does one thing. It moves value between two parties without an intermediary, and Lesson 48 showed the machinery.
It does nothing else. That is a choice, not a shortcoming.
The instructions Bitcoin can run are deliberately restricted. Its ledger records one kind of event, the movement of coins from one address to another. It does that conservatively, and the designers considered the conservatism a feature.
Simplicity is the security. Less that can be done means less that can go wrong.
Which leaves an obvious question. If a blockchain is powerful shared infrastructure, is moving currency really all it can carry?
2The Question
In 2013 a young programmer named Vitalik Buterin published a proposal built on that observation. Limiting a blockchain to currency transfers leaves most of what it could do unused.
His question was simple. What if the blockchain could run code?
The answer became Ethereum. The important thing about it is not a different currency. It is a different capability.
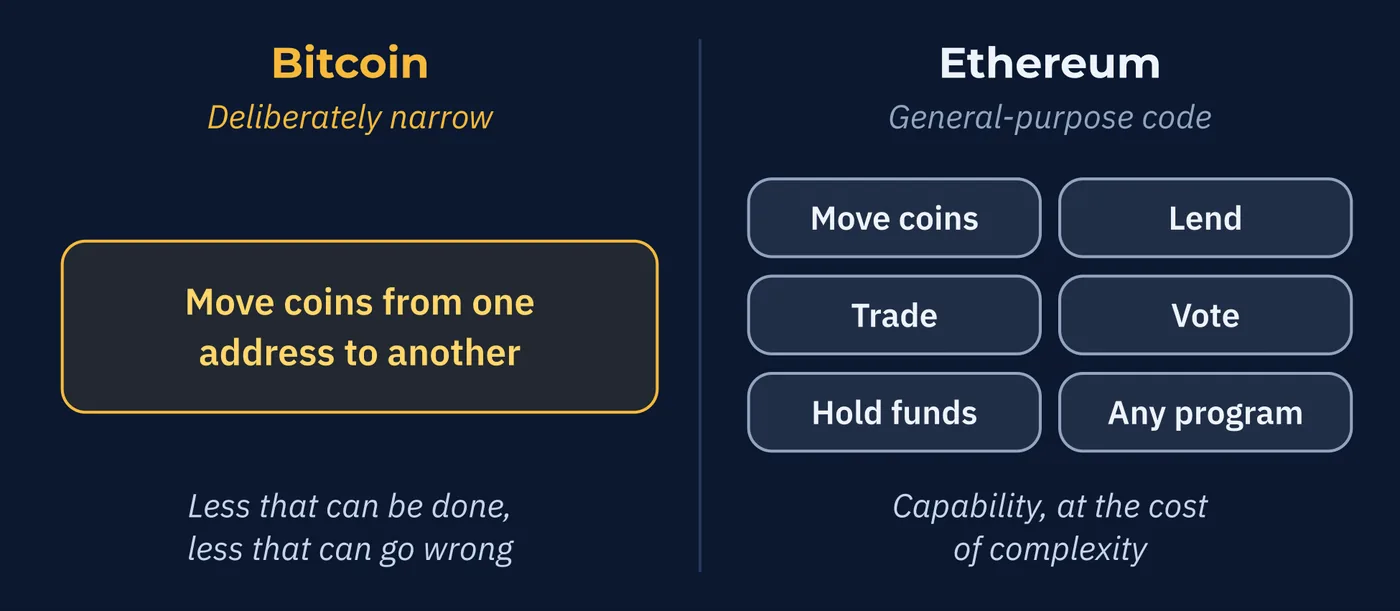
| Bitcoin | Ethereum | |
|---|---|---|
| What the ledger records | Movements of coins | Movements of coins, and the results of programs |
| What it can execute | A deliberately narrow set of instructions | General-purpose code |
| The design priority | Simplicity, and a small attack surface | Capability, at the cost of complexity |
Neither column is better. They answer different questions, and the trade-off runs both ways.
3Smart Contracts
A smart contract is a program stored on the blockchain that runs automatically when its conditions are met. It is not a legal document and the name is misleading. It is code that executes itself.
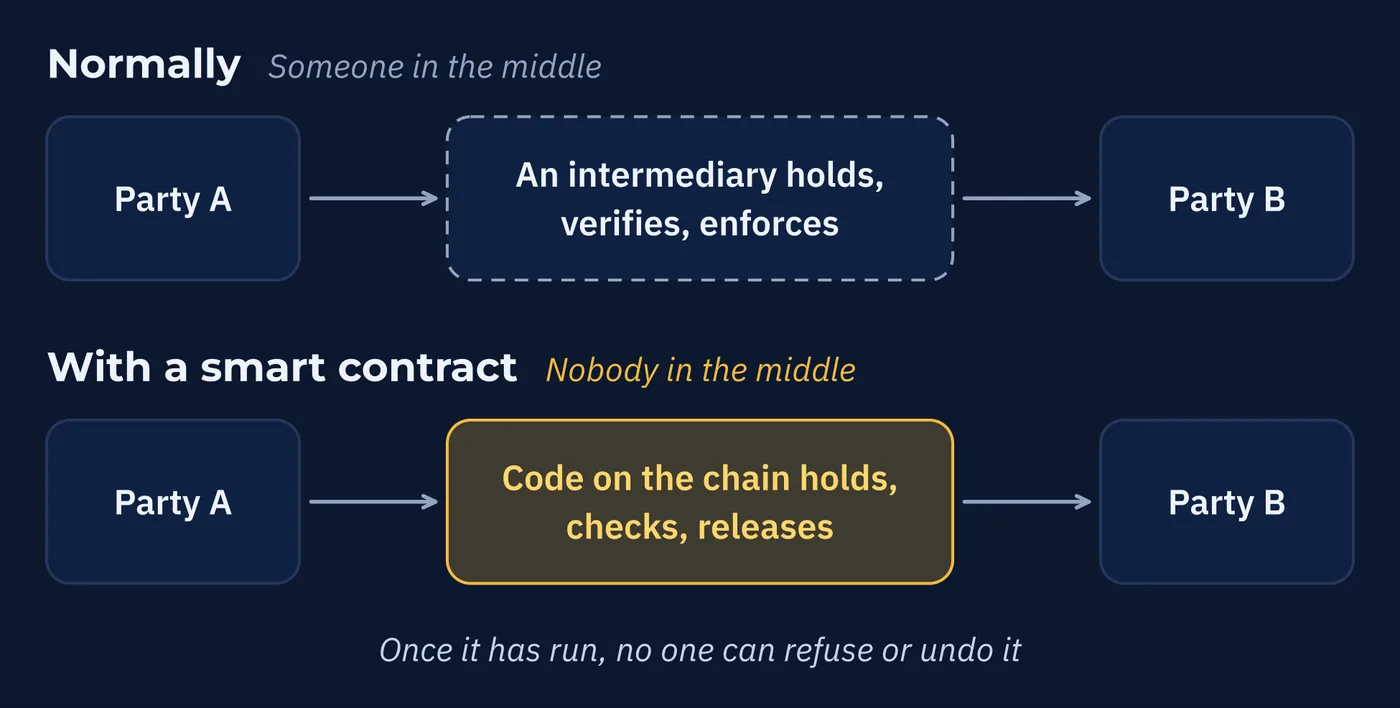
What that removes is worth examining carefully.
| Normally You Need | With a Smart Contract |
|---|---|
| Someone to hold the funds until conditions are satisfied | The code holds them and releases them |
| Someone to verify the conditions were met | The code checks, publicly and identically for everyone |
| Someone to enforce the outcome if a party refuses | There is no refusing. The code has already run. |
Once the program is on the chain and the conditions are met, the outcome is recorded and neither party can undo it. Not because anyone stops them. For the reason Lesson 48 gave. The record is permanent, and any change is visible to everyone.
4Ether Is Fuel
Ethereum's own asset is Ether, and it does a job Bitcoin's coin does not.
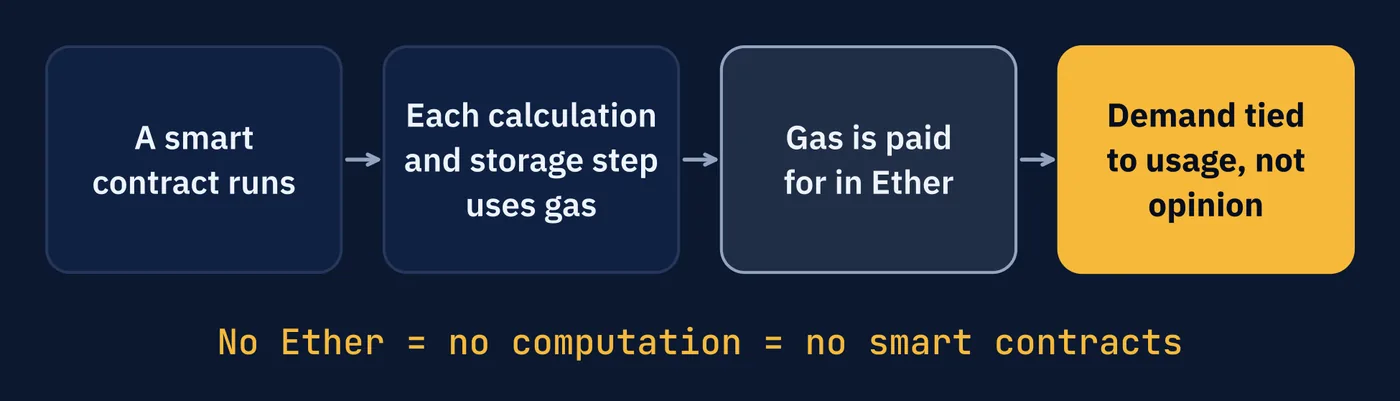
Running code costs computing resource. Every calculation a smart contract performs, every piece of data it stores, every transfer it makes, uses some of it. That resource is measured in units called gas.
The fee for that computation is paid in Ether.
no Ether = no computation = no smart contractsSo Ether has a source of demand unrelated to anyone's opinion of it as an investment. If the network is being used, Ether is being spent to pay for that use.
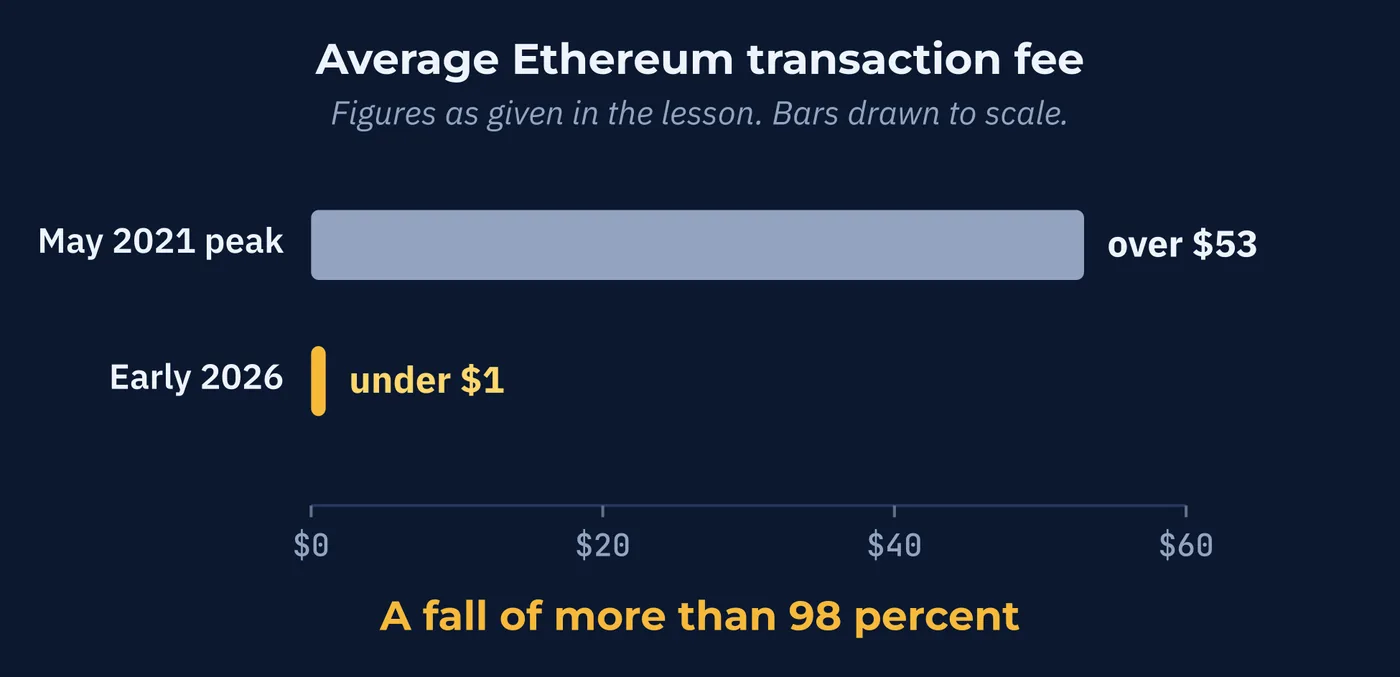
That cost has fallen sharply. At the peak in May 2021, an average transaction fee ran over fifty-three dollars. By early 2026 it was under a dollar. A decline of more than ninety-eight percent, after much of the activity moved to cheaper networks built on top of Ethereum, helped by upgrades starting with Dencun in March 2024.
5Not Bitcoin With Another Name
Which produces the practical point of this lesson for anyone watching both assets.
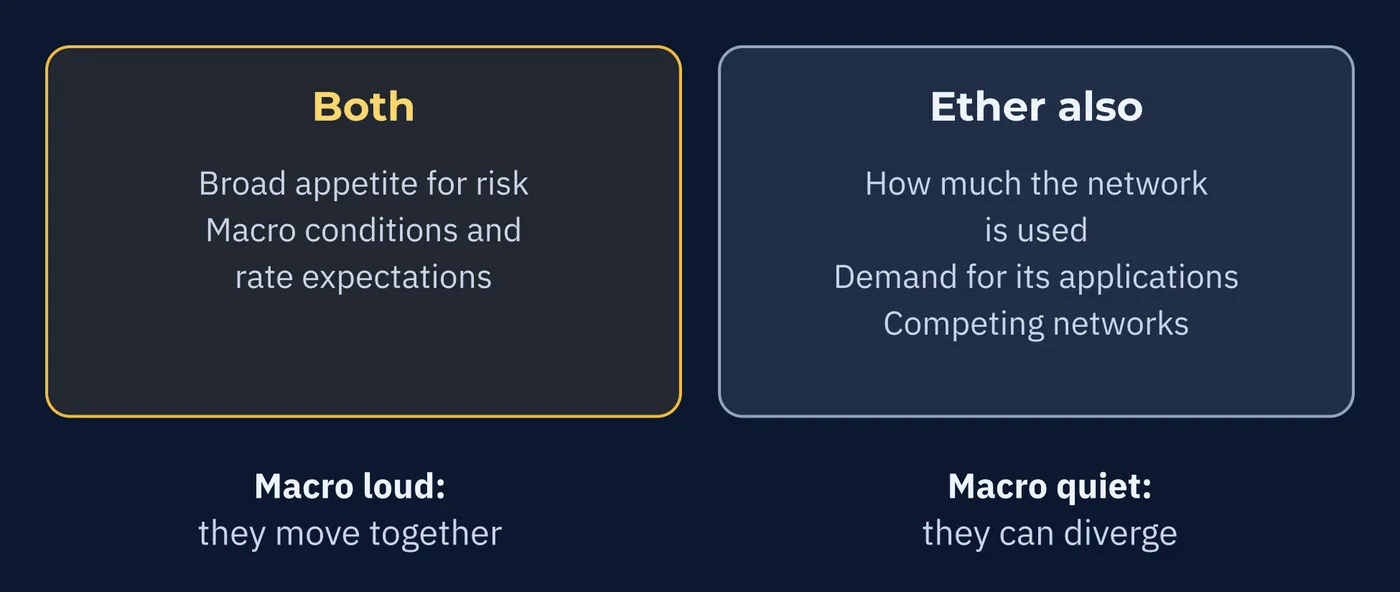
Ether and Bitcoin respond to partly different things.
| What Drives Bitcoin | What Also Drives Ether |
|---|---|
| Broad appetite for risk | How much the network is actually being used |
| Macro conditions and rate expectations | Demand for the applications built on it |
| Its fixed-supply argument | Competition from other programmable networks |
The right column is where the two can separate. When big macro forces dominate, both move together as risk assets, and Lesson 44's framework applies to each. When macro is quieter, network-specific factors get room to matter, and the two diverge.
Worth knowing before treating them as interchangeable. Lesson 46 warned that positions expressing one idea are one position. Bitcoin and Ether are usually close to that. Occasionally they are not.
6Why the Price Tells You Nothing
Now the number that matters more than price, because the mistake it prevents is extremely common.
Consider two assets.
| Price | Tokens in Circulation | Total Value | |
|---|---|---|---|
| Asset A | $10 | 10 billion | $100 billion |
| Asset B | $10,000 | 100,000 | $1 billion |
The ten-dollar asset is a hundred times larger than the ten-thousand-dollar one.
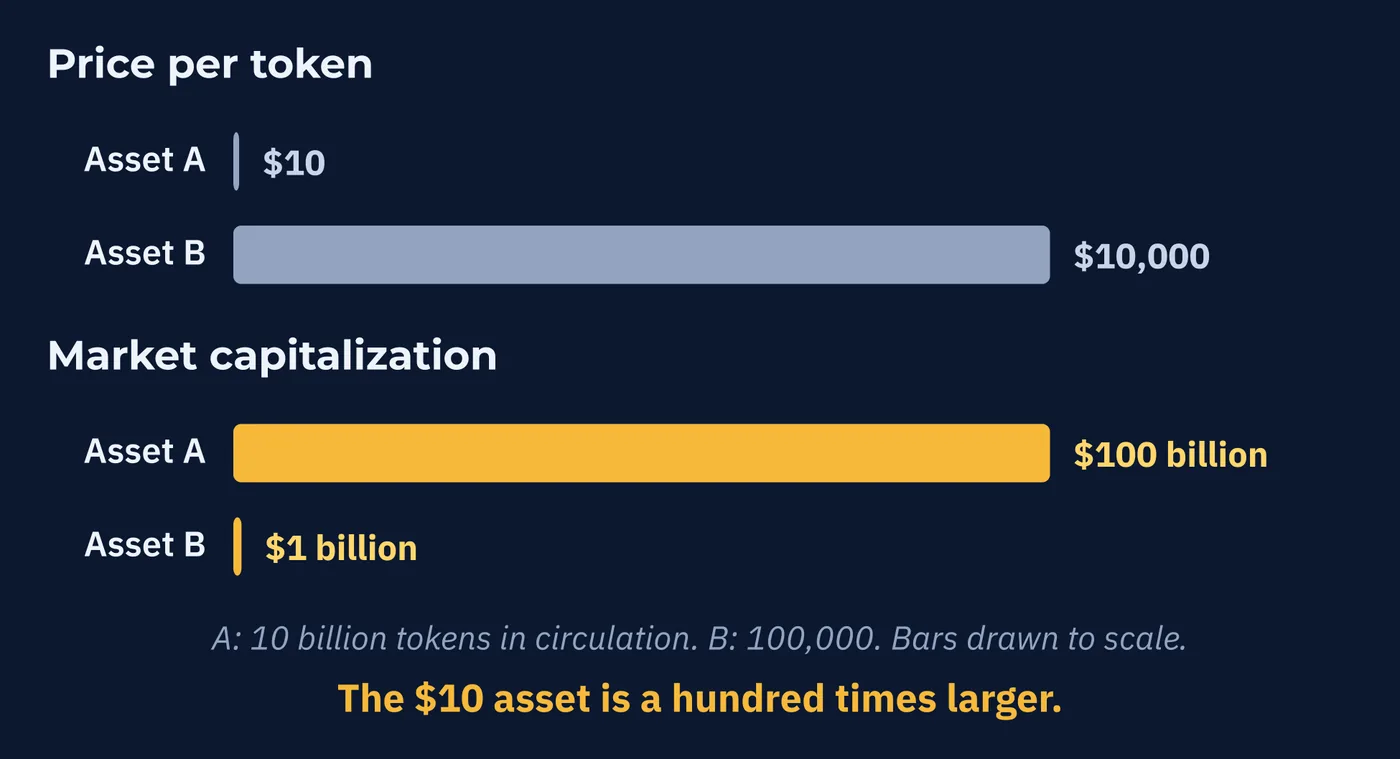
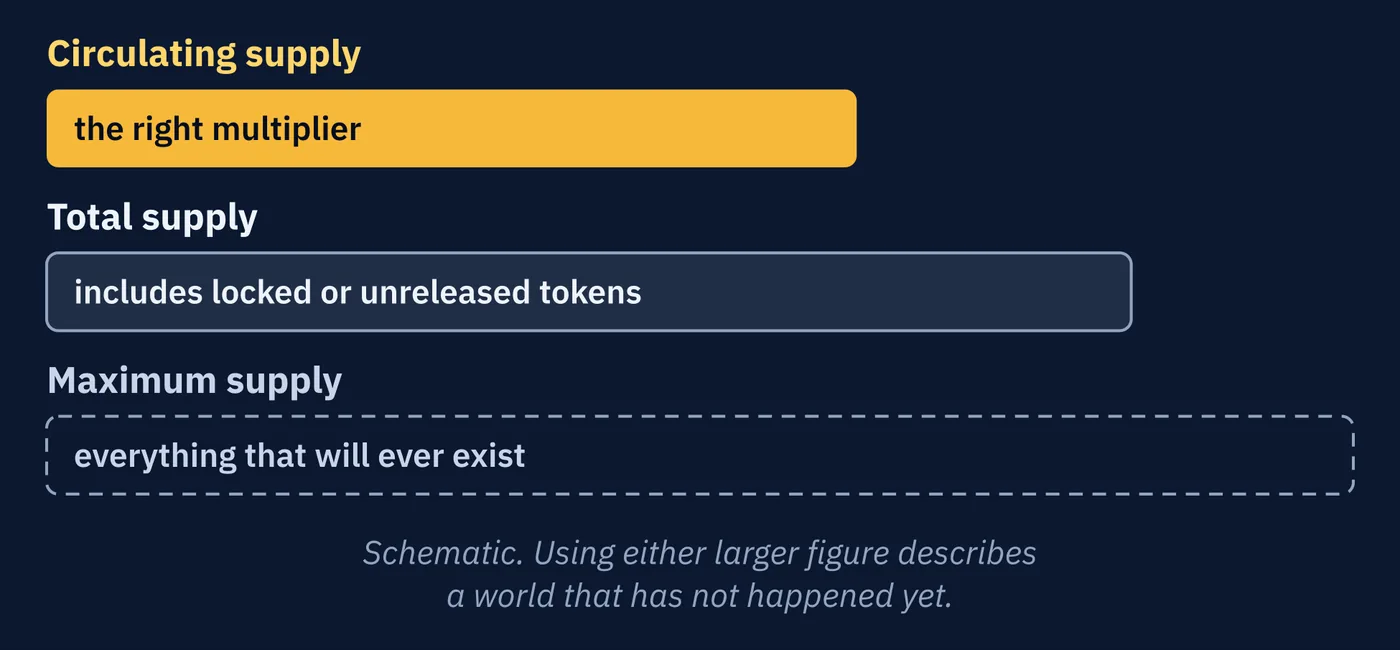
That total is the market capitalization, and it is price multiplied by the number of tokens actually in circulation. It is the only sensible way to compare the size of two crypto assets.
A token priced at a fraction of a cent is not cheap. One priced in the thousands is not expensive. Those words describe value relative to something, and price alone gives you nothing to compare against.
7Bitcoin Dominance
Market capitalization enables one more measure, and it is the most informative single number in the crypto market.
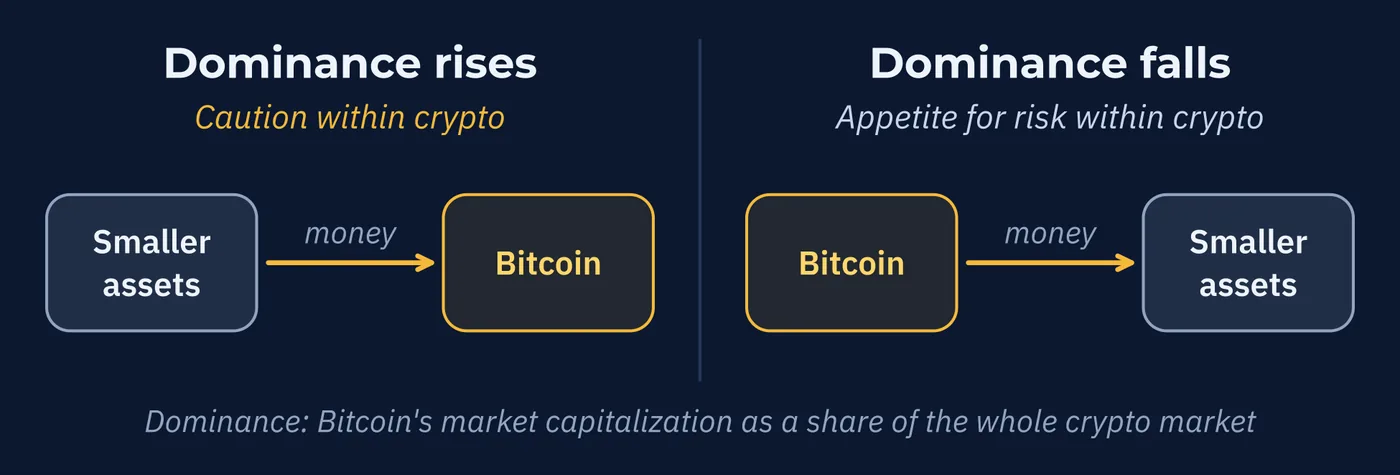
Bitcoin dominance is Bitcoin's market capitalization as a percentage of the whole crypto market.
What makes it useful is what it does during different conditions.
| When Dominance | It Means | Which Signals |
|---|---|---|
| Rises | Money is moving from smaller assets into Bitcoin | Caution within the crypto market |
| Falls | Money is moving from Bitcoin into smaller assets | Appetite for risk within the crypto market |
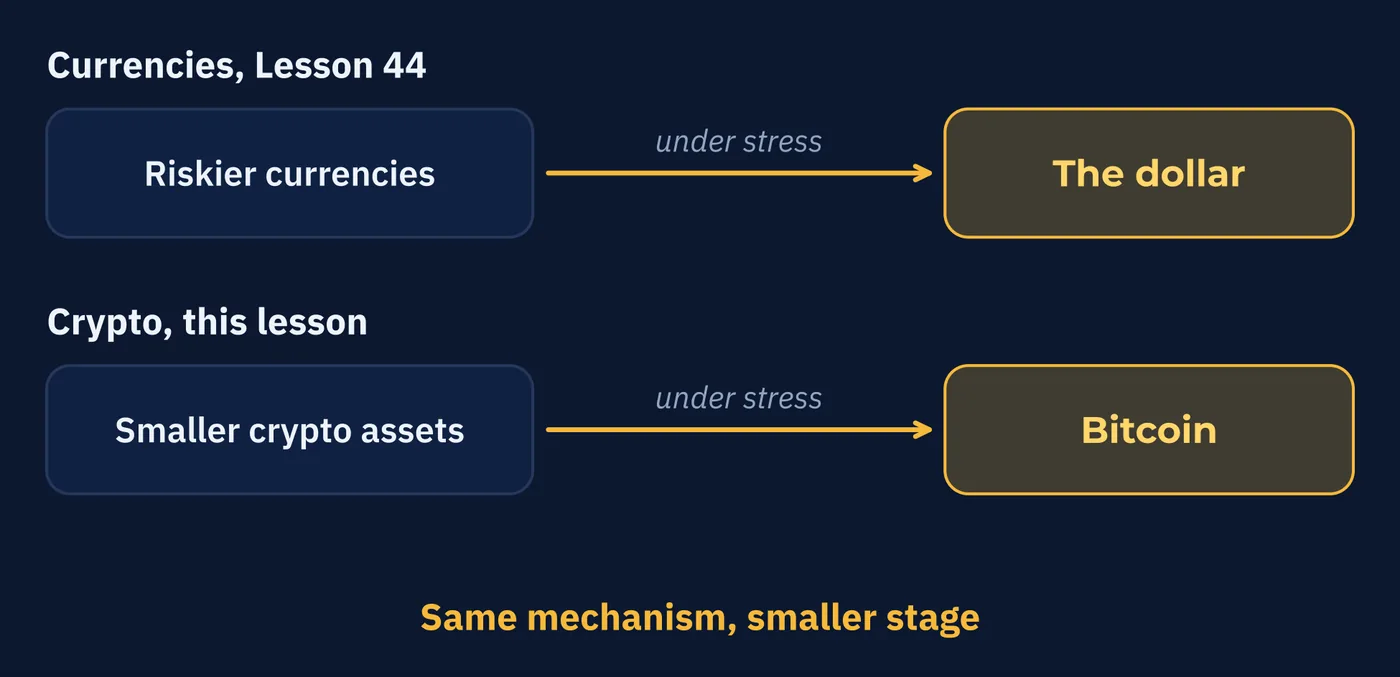
Read that against Lesson 44 and the pattern should look familiar.
That lesson described safe haven behavior, where money consolidates into the most established and most liquid currency when stress arrives. This is the same thing inside one asset class. Bitcoin plays the relative safe haven among crypto assets.
Same mechanism, smaller stage. Which is a useful demonstration that the frameworks in this course are not specific to currencies.
8What Is Actually Different Here
One closing observation, and it is a genuine advantage rather than a promotional claim.
Lesson 40 established that the currency market has no consolidated record. No single tape. No complete picture. Every participant sees a derived slice of the whole.
A blockchain is the opposite. Every transaction is recorded publicly, permanently, and identically for everyone. Anyone can read the whole history with no permission, no account, and no fee.
Currency markets have no complete record. Blockchains are nothing but the record.
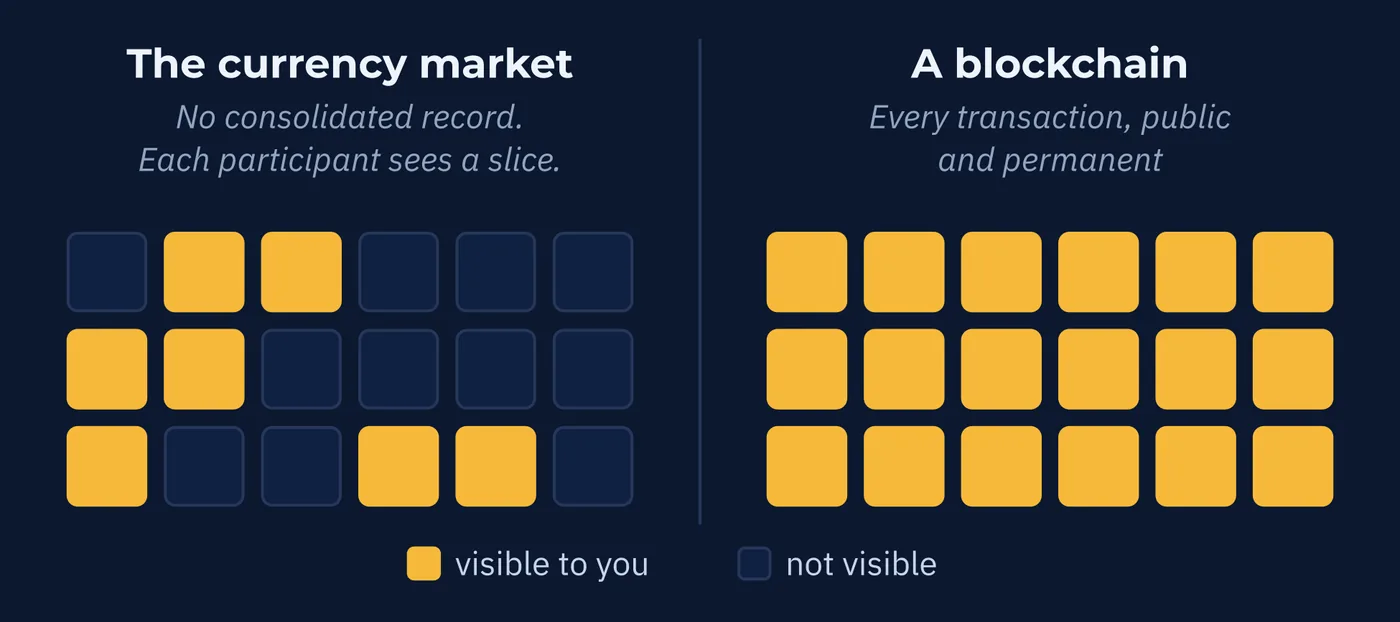
That transparency is architectural rather than a policy anyone chose. It produces a category of public information with no equivalent in currency trading.
The next lesson takes one application of all this and examines it properly. Stablecoins. Lesson 11 introduced them as the quote currency of crypto trading, and Lesson 35 fitted them into a framework about pegs. They deserve a lesson of their own.
Three Things to Remember
Try This
Fifteen minutes. The first step usually surprises people.
Words From This Lesson
| Term | What It Means |
|---|---|
| Smart contract | A program stored on a blockchain that runs automatically when its conditions are met. |
| Ether | Ethereum's native asset, used to pay for computation on the network. |
| Gas | The unit measuring computational resource consumed by an operation on Ethereum. |
| Market capitalization | Price multiplied by circulating supply. The correct way to compare the size of crypto assets. |
| Circulating supply | Tokens actually in active circulation. The right denominator, unlike total or maximum supply. |
| Bitcoin dominance | Bitcoin's market capitalization as a percentage of the whole crypto market. |
| On-chain data | Information readable directly from the public blockchain, available to anyone without permission. |
Test Your Knowledge
Eight questions. Answer them all before checking the key on the following pages. If a question gives you trouble, the answer key tells you which section to revisit.
- A. The technology could not support more
- B. Simplicity reduces what can go wrong
- C. Regulators required it
- D. Its creator ran out of time
- A. A larger maximum supply
- B. Faster transaction settlement only
- C. It can execute general-purpose code
- D. It has no fixed supply limit
- A. A program on the blockchain that runs automatically when conditions are met
- B. A legal agreement stored digitally
- C. A contract reviewed by automated legal software
- D. An agreement between two exchanges
- A. Any form of payment
- B. Public record keeping
- C. Internet access
- D. A third party to hold funds, verify conditions, and enforce outcomes
- A. Voting on protocol changes only
- B. Paying for computation, measured in gas
- C. Backing the value of other tokens
- D. Nothing, it is purely speculative
- A. Asset A, by a factor of about 100
- B. Asset B, by a wide margin
- C. They are roughly equal
- D. It cannot be determined
- A. Maximum supply
- B. Total supply
- C. Circulating supply
- D. Whichever produces the larger figure
- A. A change in Bitcoin's supply schedule
- B. Bitcoin's price rising in absolute terms
- C. Increased appetite for smaller assets
- D. Money rotating from smaller assets into Bitcoin, indicating caution
Answer Key
Each answer explains why the correct choice is correct, why the others are not, and where to reread.
Question 1 · correct answer B
The restricted instruction set is a design choice. Fewer things a system can do means fewer ways it can be attacked or fail unexpectedly.
A reverses it, since the limitation was chosen rather than imposed by capability. C is wrong because no regulator specified the design. D treats a deliberate decision as an accident.
Review: Section 1, Deliberately Limited
Question 2 · correct answer C
Ethereum's defining feature is capability rather than currency. It can run general-purpose programs, which Bitcoin's deliberately narrow instruction set cannot.
A and D describe supply arrangements, which are not the distinguishing feature. B describes a performance difference rather than a difference in what the network can do.
Review: Section 2, The Question
Question 3 · correct answer A
It is code stored on the blockchain that executes itself when its conditions are satisfied. The name is misleading, since it is neither a contract nor especially smart.
B describes a document rather than executing code. C describes software assisting lawyers. D describes a commercial arrangement between companies.
Review: Section 3, Smart Contracts
Question 4 · correct answer D
The code holds the funds, checks the conditions publicly, and produces the outcome. Nobody needs to approve it and no party can refuse after the fact.
A is wrong because value still changes hands. C is wrong because the network requires connectivity. B reverses it, since the record is more public rather than less.
Review: Section 3, Smart Contracts
Question 5 · correct answer B
Every operation consumes computational resource measured in gas, and the fee for that is paid in Ether. Without it, smart contracts cannot execute.
A describes one possible use of some tokens but not Ether's core function. C describes a backing role Ether does not perform. D ignores a genuine utility tied to network usage.
Review: Section 4, Ether Is Fuel
Question 6 · correct answer A
Ten dollars times ten billion tokens is one hundred billion. Ten thousand dollars times one hundred thousand tokens is one billion. The cheaper-looking asset is a hundred times larger.
B relies on price alone, which is the error this section corrects. C ignores a hundredfold difference. D is wrong because both figures are given and the arithmetic is straightforward.
Review: Section 6, Why the Price Tells You Nothing
Question 7 · correct answer C
Only tokens in active circulation should be counted. Including locked or unreleased tokens describes a state of the world that has not happened yet.
A and B both inflate the figure by counting tokens not yet in circulation. D describes a motive for choosing badly rather than a correct method.
Review: Section 6, Why the Price Tells You Nothing
Question 8 · correct answer D
Dominance rising means Bitcoin is gaining share of the total, which happens when capital consolidates into the most established asset. That mirrors safe haven behavior from Lesson 44.
B confuses share with price, and dominance can rise while Bitcoin falls if others fall further. C reverses it. A is unrelated, since the supply schedule is fixed and known.
Review: Section 7, Bitcoin Dominance
Keep going
Crypto From First Principles is written by Kanin D. Alldredge for The Currency Classroom, and it is free to read. There is more free from CNS: start here.
Start free with CNS →